



Written by: Thejaswini M A
Compile: Block Unicorn
Foreword
We tried everything.
NFTs were meant to attract creators. Web3 games promised to bring blockchain to the masses. Social protocols like Farcaster and Lens promised a decentralized future for digital communities. Zora aims to prove that content can be a financial asset. Friend.tech turned social capital into something truly tradable. Meme coins—well, no one said they were building civilization, but someone always claims they’ll bring the next wave of retail investors.
NFTs were originally designed to attract creative talent. Web3 games promise to bring blockchain to the masses. Social protocols like Farcaster and Lens herald a decentralized future for digital communities. Zora aims to prove that content can become a financial asset. Friend.tech makes social capital truly tradable. As for meme coins—while no one claims they will build civilizations, someone always says they’ll bring the next wave of retail investors.
Additionally, there are prediction markets. Polymarket may be the product we’ve come closest to a true breakthrough with, but its peak coincided with the U.S. election cycle. The open question now is whether it can maintain user engagement when the stakes are smaller. There’s also an unspoken truth that few are willing to admit: the platform’s accuracy stems in part from users with access to real information trading on it. This presents a challenging issue for regulators and ordinary users alike.
We now arrive at March 2026. Bitcoin has been heavily custodied by institutions (we’ll set aside the exact figures for now). Stablecoins have been standardized overnight by the GENIUS Act. Infrastructure has never been more mature. If you open the App Store and filter the “Finance” category, the top-ranked cryptocurrency apps are Coinbase, Kraken, and Crypto.com—all of which are trading platforms that have been operating for over a decade. Truly transformative consumer applications are still missing.
Why?
Why haven't we reached our goal yet?
The cryptocurrency industry follows intense bull and bear cycles. Most innovations only become known during market crashes. The public often associates cryptocurrencies with chaos. When Bitcoin crashes, people say, “I told you so.” They don’t understand how it actually works. But we can’t blame them for that. After all, the signal-to-noise ratio in cryptocurrency is simply too poor.
Cryptocurrency was never designed for the masses. Developers focused on their own ideological paths—decentralization, censorship resistance, and autonomy—expecting the public to gradually adopt them. But the public never asked for these things. They wanted faster payments, higher savings interest rates, and more convenient international money transfers. Instead, cryptocurrency offered mnemonic phrases, gas fees, and declarations aimed at dismantling the existing financial system.
Meanwhile, the world outside cryptocurrency has undergone dramatic changes. Artificial intelligence (AI) has dominated public discourse; ChatGPT attracted 100 million users in just two months. People who had never heard of Transformers are now using AI every day. Cryptocurrency, however, has not experienced a similar surge. The technology once seen as the next generation of the internet has ultimately been overshadowed by something that truly feels like the next generation of the internet.
Trust crises have followed one after another, and macroeconomic volatility has become the norm. Within the cryptocurrency space, a constant stream of scandals has validated the concerns of skeptics. Do Kwon and Terra Luna, Three Arrows Capital, Celsius, FTX—every few months, another “reputable” crypto company is exposed for insolvency or misuse of customer funds. Regulatory responses, such as “Operation Killswitch 2.0,” and the U.S. Securities and Exchange Commission’s (SEC) narrow focus on enforcement have only pushed legitimate projects overseas while doing little to curb actual fraud, worsening the situation.
Another very important point is: the user experience still does not meet consumer-grade standards.
Compare the user experience of a crypto social app to Instagram: On Instagram, you download the app, sign up with your phone number, and log in immediately. Content is visible right away—intuitive and easy to use, with no learning curve.
Now, let’s compare Farcaster or Lens. First, you need a wallet: write down the 12-word mnemonic on paper and store it securely. If you lose your wallet, everything is gone forever, with no customer support to contact. Then, you need ETH to pay gas fees to create your profile. You must understand what gas is, why it fluctuates, and why the same action might cost $5 one time and $50 another. You must connect your wallet, approve transactions, sign messages you don’t understand, and hope you don’t accidentally click on a phishing site. Only after completing all these steps can you begin using social features—features that still lack algorithmic feeds, creation tools, and network effects, which are precisely what make Instagram appealing.
Alternatively, setting up a digital wallet is like opening a Cash App: download, enter your phone number, link your bank account, and you’re done. Three steps, five minutes.
What about a crypto wallet? You must choose from dozens of options (MetaMask, Phantom, Coinbase Wallet), download the wallet, generate a mnemonic phrase, write it down, store it securely, understand the difference between Layer 1 and Layer 2, fund it with cryptocurrency from an exchange (which requires KYC and bank transfers), and then learn how to manage gas fees, approve token permissions, and avoid various scams.
For most people, this is just a wall.
The friction is immense, but developers don’t feel it. The entire loop—who develops, who tests, who provides feedback, who invests—is highly closed off. When your test users all have MetaMask installed and understand gas fees, you simply won’t perceive the friction that prevents average users from adopting MetaMask. It’s like asking a fish to notice water.
Cemeteries are insightful; graveyards are meaningful.
Friend.tech attempted to financialize social relationships. Its business model involved buying and selling "keys" to access private chats with cryptocurrency influencers. At its peak, the platform generated $90 million in trading volume, which then plummeted to $71 million per day, ultimately leading the developers to abandon the project. The issue wasn't with the technology itself, but rather that no one truly wanted their social graph to become a financial instrument.
Farcaster raised $150 million from a16z to build a decentralized social media platform. The founders, formerly of Coinbase, possess genuine technical expertise. Daily active users briefly peaked at 100,000 before plummeting to just 4,360 active users. Monthly revenue also dropped to $10,000. The founders eventually left Farcaster to launch a stablecoin company. The issue? No one cared whether their “Twitter alternative” was truly decentralized.
During the COVID-19 pandemic, Axie Infinity established a fully functioning parallel economy in the Philippines, where players earned incomes above the minimum wage by breeding digital creatures. Later, the token economy collapsed, and everyone stopped playing. The issue wasn’t the game mechanics—it was that no one wanted to play a game that felt like a job unless they desperately needed the money.
Who is actually doing this right now?
The companies closest to achieving true consumer success are financial platforms that integrate cryptocurrency channels.
Coinbase
Coinbase is building what CEO Brian Armstrong calls the "everything exchange." As part of its 2026 roadmap, this is listed as the company’s top priority—integrating cryptocurrencies, stocks, prediction markets, and commodities across spot, futures, and options trading.
The products they launched:
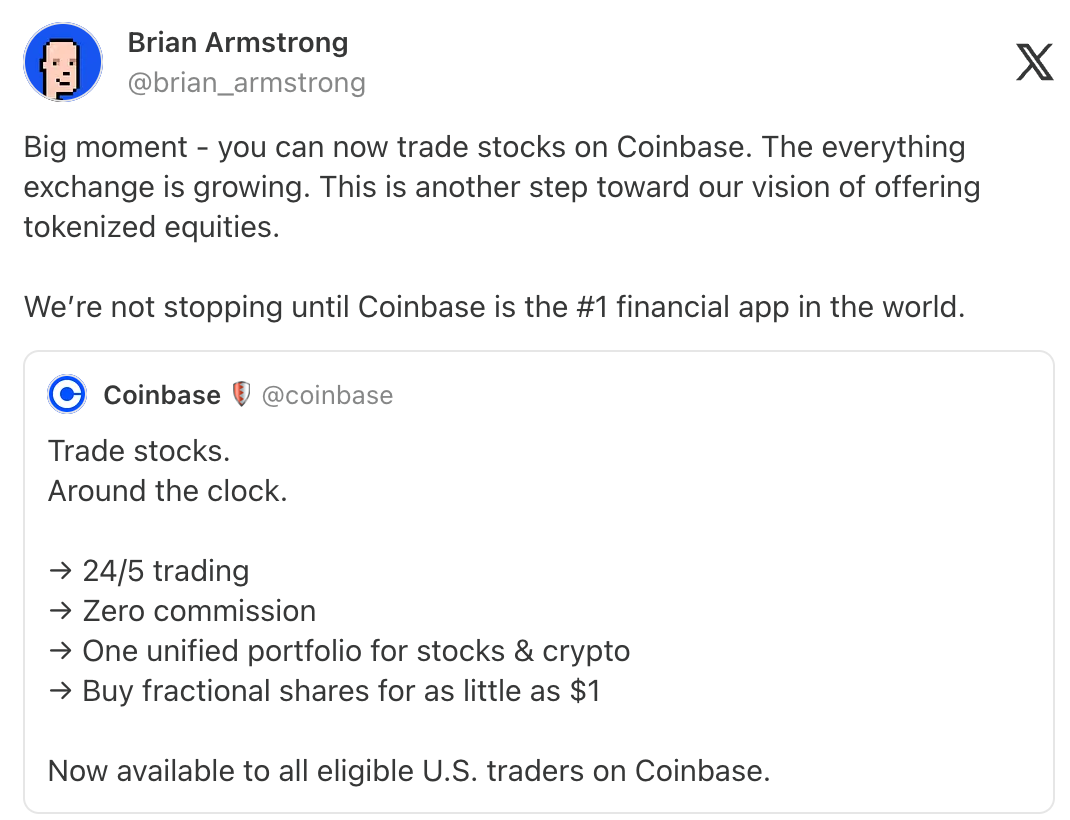
Stock trading. Zero-commission stock trading. Trade cryptocurrencies within the same app, 24/7, five days a week. Their messaging focuses not on “learn about blockchain,” but on “trade everything in one place.”
Predictive markets integrated via Kalshi. You can place bets on elections, Federal Reserve decisions, and sports outcomes without leaving Coinbase. The cryptocurrency portion is fully transparent.
Perpetual futures for international users. Borrowing functionality allows users to borrow up to $5 million against BTC collateral and up to $1 million against ETH collateral. Additionally, token presales will be launched, enabling retail users to purchase tokens with USDC prior to listing.
Brands can create their own branded stablecoins backed by USDC. Stablecoin payment functionality is integrated into Shopify, with Checkout.com and PPRO set to launch in 2026. UK savings accounts offer an annual interest rate of 3.75% and are protected by the FSCS. They are applying for a national trust charter, which will grant them expanded banking permissions.
Coinbase is building infrastructure to enable everyone to access blockchain technology. This includes not only a super app for its users, but crucially, also Rails backend support for institutions, fintech companies, and traditional banks entering the cryptocurrency space.
Base holds over $7 billion in on-chain assets. cbBTC has become the second-largest asset, valued at approximately $2.5 billion. Its integration with Morpho has enabled $2 billion in collateral to support over $1 billion in loans.
Robinhood
Robinhood’s trajectory is the opposite: it began as a stock trading app and is now rapidly evolving into a full-stack cryptocurrency platform.
The features they have launched include: ETH and SOL staking for U.S. users; perpetual futures with up to 7x leverage for European users; and over 1,000 tokenized stocks, U.S. stocks, and ETFs for EU customers, offering 24/5 round-the-clock trading with zero commissions. Their Ethereum Layer-2 blockchain, "Robinhood Chain," built on Arbitrum, is currently in online testing.
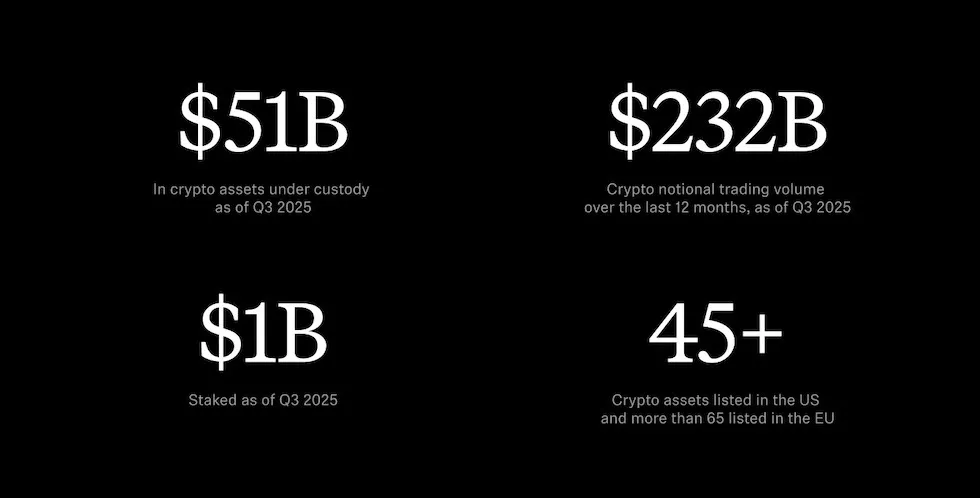
As of the third quarter of 2025, the total value of custodied crypto assets reached $51 billion. Over the past twelve months, the notional trading volume of cryptocurrencies amounted to $232 billion. An AI assistant named Cortex provides insights and market analysis for Gold members. A cashback credit card that automatically converts rewards into cryptocurrency. Staking is positioned as the "core feature" and primary driver of user engagement in 2026.
They acquired Bitstamp to strengthen global cryptocurrency infrastructure. They are expanding into Indonesia. They are developing Robinhood Social, a platform where traders can share their actual trades and profit and loss information.
They already have the infrastructure for a new bank, including direct deposit, credit cards, and cash management, with cryptocurrency added on top.
Then comes the favorite of cryptocurrency enthusiasts:
Hyperliquid processed $2.8 trillion in perpetual futures trading volume in 2025. The company ranked among the Forbes Fintech 50 without any funding. This may be the most successful consumer product case in the cryptocurrency space.
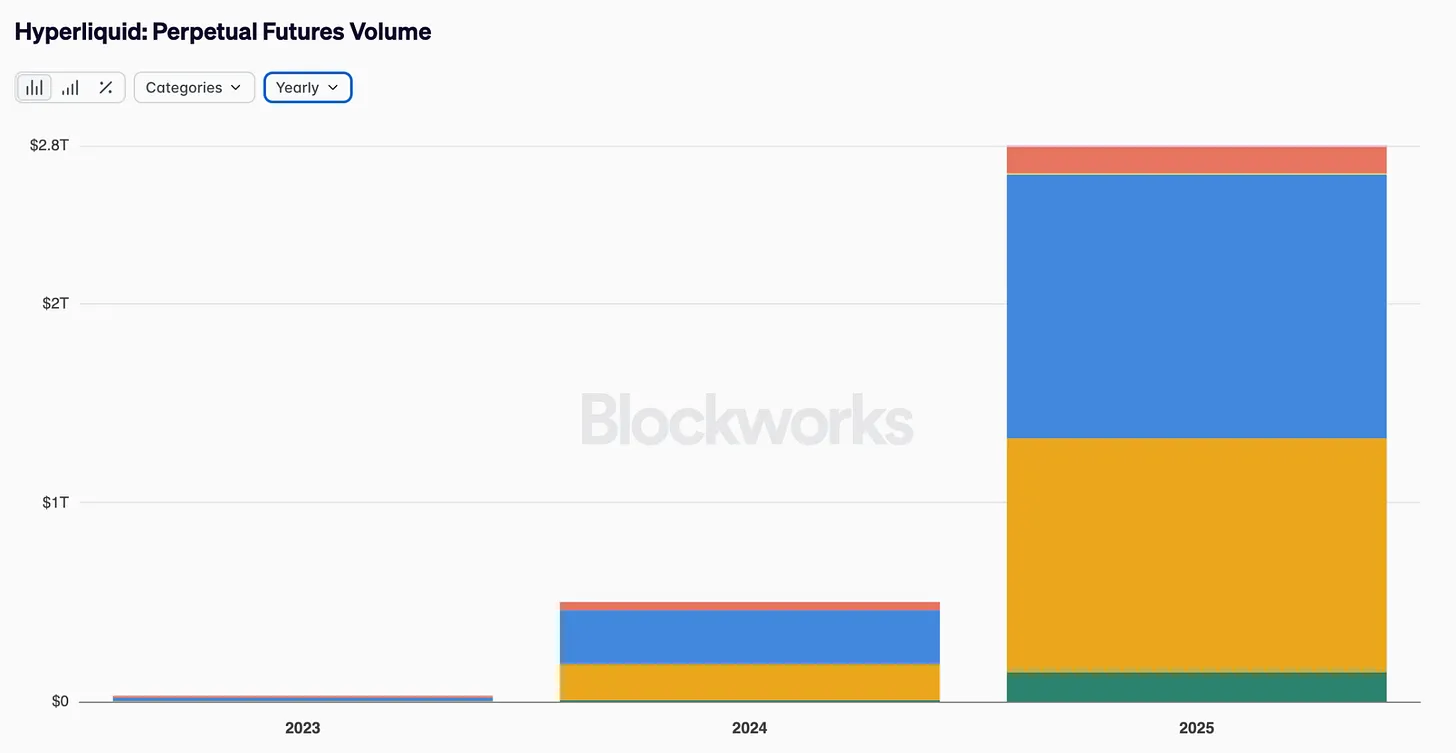
However, Hyperliquid is not a consumer-facing breakthrough technology, but rather a success story within the cryptocurrency space. It serves users who already understand perpetual futures, leverage, and order book dynamics. Its trading volume primarily comes from traders already active in cryptocurrency markets seeking better execution. Hyperliquid simply provides existing users with a superior trading platform.
What are we missing?
What should an ideal cryptocurrency consumer application actually look like? Don’t speak generally—provide specific details.
Stealth wallet. No need to worry about seed phrases. Social recovery or biometric security. Progressive custody—start with simple, user-friendly features and gradually enhance security as your balance grows. The technology already exists: account abstraction, passkeys, smart contract wallets. But adoption has been slow because developers have prioritized the purity of decentralization over user experience.
Seamless fiat on- and off-ramps. Instant settlement. No need to wait 3–5 business days for ACH transfers. No need to understand the difference between USDC and USDT. No minimum deposit requirements. Just link your bank account to transfer funds.
No complex jargon. Say “Send $50 to Sarah,” not “Enter recipient address and set gas limit.” Use natural language to understand your intent. Includes error recovery to undo transactions or cancel pending actions.
The interface is simple and intuitive—not as complicated as operating a spacecraft. All actions, including payments, exchanges, yield inquiries, and social features, require just one click. It gently introduces crypto concepts to users who want to learn, while offering a fully abstracted interface for those who don’t.
A consumer-facing layer of trust. AI-driven risk alerts warn you, “This looks like a scam,” before you approve a transaction. Automated portfolio management that optimizes DeFi yields. Streamlined, automated tax reporting. The safeguards ordinary people expect from financial products.
Compliance features are built into the system but are invisible to users. The selective disclosure feature allows you to share specific balances without revealing your full wallet. Transaction privacy can be protected by masking transfers when necessary. Identity protection uses pseudonyms by default. Data sovereignty features enable users to control all their personal information.
A compelling narrative that explains why this matters, without relying on any belief system—not “overthrowing the financial system” or “being your own bank,” but “it does better what you’re already doing.”
It shouldn’t feel like you’re “using cryptocurrency”—it should feel like a better banking app.
The problem is that most cryptocurrency applications are developed, tested, and funded by crypto insiders. When all your test users have MetaMask installed and understand gas fees, you don’t experience the friction that prevents broader adoption.
Cryptocurrencies solve problems that don't exist for the majority in developed economies. Self-custody and censorship resistance are indeed important principles. But for those with regular bank accounts and stable currencies, these are abstract threats, not everyday pain points. The marketing focus of cryptocurrencies is on "you should want it because of the potential impact it could have," rather than "it delivers tangible benefits right now." This argument simply doesn't hold up against competition from Venmo and Cash App.
What did we overlook?
We often assume that cryptocurrency has failed because it lacks flashy consumer applications. But upon closer inspection, its infrastructure is already highly mature.
Stablecoins work. They are fully functional infrastructure that transfers real value across borders every day. Security has improved significantly. Smart contract audits have become a standard practice. Multi-signature wallets are widely adopted. Insurance protocols are in place. The catastrophic hacks of 2021–2022 have occurred far less frequently as the industry has learned hard lessons.
DeFi trading platforms are highly efficient. Protocols such as Uniswap, Aave, and Compound can process tens of billions of dollars in trading volume with minimal downtime. The total value locked in DeFi platforms exceeds $300 billion. Institutional investors are leveraging these platforms to enhance efficiency.
Institutions are leveraging this technology. BlackRock has launched a tokenized money market fund. JPMorgan handles blockchain-based repurchase transactions. Traditional financial institutions are also quietly using crypto infrastructure, as it is more efficient than traditional systems in certain use cases.
Liquidity is deeper than ever. The bid-ask spreads that plagued early DeFi have narrowed significantly. Arbitrage bots ensure efficient price alignment across exchanges, while professional market makers provide ample liquidity.
Institutional users adopted cryptocurrency before retail users. This is unusual but crucial. If you believe that artificial intelligence represents the future, then AI agents need stablecoins. They require programmable settlement systems. They need cryptocurrency infrastructure. Chris Dixon also agrees that AI agents need programmable money, which traditional banks cannot provide. As AI becomes widespread, cryptocurrency infrastructure will become essential infrastructure. Therefore, the infrastructure may be more important than the hype. The foundation is already in place; what is lacking is not technology.
Crypto spending apps will ultimately prevail, but only if they stop trying to pretend to be crypto.
Applications that truly stand out won’t ask people to “use cryptocurrency”—they’ll offer genuinely better solutions to problems people already face: higher savings yields, faster payments, lower transfer costs, portable identity, and true ownership.
Bank accounts feel familiar, and the interface is highly intuitive. Behind the scenes, stablecoins are settled, smart contracts are executed, and the blockchain provides final confirmation—all without users needing to lift a finger.
Each generation creates tools they don’t fully understand. The people who laid the transatlantic telegraph cable in 1858 believed they were simply building a faster way to transmit information. They likely never imagined they were constructing the nervous system of the global economy.
We often judge new infrastructure by the first things built on it—and those first things are almost always wrong. They’re merely old concepts dressed in the clothing of new technology, like horseless carriages, moving photographs, and electronic newspapers.
True change happens afterward, when someone raised alongside the infrastructure builds something that could not have existed without it—something the original builders never imagined.
Ten years from now, the applications they develop will be radically different from what we discuss today on cryptocurrency Twitter. It won’t be an improved version of existing products, but something we currently cannot even describe in words.
Our current task is not to build that thing—we can’t do it. Our task is to ensure the infrastructure is in place, functioning properly, and available for others to build upon in the future without needing to read the whitepaper.
Finance is the means by which we achieve our goals, because it empowers enough people with the necessary tools, enabling the true builders—those we haven’t yet met—to get started.
This is the real strategy that works—neither transformation nor surrender. We're simply constantly distracted by trivial matters.
The most important cryptocurrency application has yet to be imagined. And this is precisely what makes me most optimistic about this industry.