

KuCoin Ventures Weekly Report: Rising Inflation and Oil Prices Lift Rate-Hike Expectations, While Crypto ETF Flows Diverge and TradFi-Crypto Infrastructure Integration Accelerates
1. Weekly Market Highlights
TradFi and Crypto Continue to Converge: Rules, Assets, and Credit Infrastructure Advance in Parallel
This week, the convergence between traditional finance and crypto continued to extend from the product layer into broader financial infrastructure. The U.S. crypto market structure bill, the CLARITY Act, entered a new procedural stage; Nasdaq announced a proposed $100 million investment in Kraken’s parent company, Payward, while continuing to advance tokenized equity infrastructure; and Tether partnered with UK-based asset manager Fasanara Capital to launch the private credit fund StableFund. Although these developments appear separate, they correspond to three key layers of on-chain finance — rules, assets, and credit — and suggest that industry attention is gradually shifting from “how assets are issued and traded” toward a more complete financial market infrastructure.
On September 10, Nasdaq Ventures announced a proposed $100 million investment in Kraken’s parent company, Payward, further deepening the tokenized equity partnership the two sides began in March this year. The partnership will continue to advance the integration of Nasdaq Equity Tokens, or NETs, with Payward’s xStocks ecosystem, while Payward will also adopt Nasdaq’s market surveillance technology. Nasdaq expects NETs to launch in the second quarter of 2027, with the next phase of cooperation also covering the global distribution, trading, and post-trade processing and settlement of tokenized equities.
Many existing tokenized equity products have primarily focused on creating an on-chain representation of the underlying asset’s price. Nasdaq’s NETs, by contrast, place greater emphasis on preserving the existing rights and protections of issuers and investors, while connecting regulated traditional markets with on-chain trading environments. Nasdaq also brings capabilities from traditional capital markets across areas such as market surveillance, governance, and post-trade processing and settlement.
Meanwhile, stablecoins are also moving further into traditional credit markets. On September 9, Tether and Fasanara Capital announced the launch of StableFund, an evergreen private credit fund backed by a combined $400 million of cornerstone capital from the two parties, with plans to attract up to $3 billion of additional third-party institutional capital. Fasanara will be responsible for investment management, allocating capital to short-duration, asset-backed credit through its fintech lending network spanning more than 60 countries. Tether, meanwhile, will act as co-sponsor, financing opportunity originator, and advisor, identifying USDT-related financing opportunities while providing stablecoin infrastructure for capital inflows and outflows, treasury management, and settlement.
This suggests that stablecoin use cases are expanding beyond payments and trading into capital allocation and the broader credit value chain. Historically, stablecoins have primarily addressed the problem of moving money more quickly and with lower friction across platforms and borders. StableFund represents an attempt to embed these settlement capabilities more deeply into private credit fundraising, lending, and treasury management processes. It also reflects Tether’s ongoing efforts to connect its stablecoin network, funding channels, and cross-border settlement capabilities with real-world credit assets.
Taken together, these developments suggest that the focus within RWA and on-chain finance is broadening beyond tokenization projects alone toward issuance and registration, trading and liquidity, settlement, credit, and the intermediary infrastructure connecting traditional finance with on-chain markets. Projects that can genuinely integrate into the operating workflows of existing financial institutions and demonstrate measurable improvements in capital efficiency, distribution efficiency, or settlement efficiency may ultimately be more important to track than the “asset tokenization” narrative itself.
2. Weekly Selected Market Signals
Inflation and Oil Prices Revive September Rate-Hike Expectations, 10-Year Treasury Yield Nears 5%, U.S. Equities Pull Back from Highs, and Crypto ETF Flows Remain Structurally Divergent
U.S. inflation data for August renewed market expectations for a September rate hike. PPI rose 0.4% month-on-month and 5.4% year-on-year, with energy costs as a major driver. CPI subsequently increased 0.4% month-on-month and 3.4% year-on-year, while core CPI rose 0.3% month-on-month and 2.4% year-on-year. Combined with renewed Middle East tensions pushing crude oil back above $100 per barrel, markets have become increasingly concerned that higher energy costs could continue to feed through into goods, transportation, and service prices.
By the end of the week, the CME FedWatch Tool showed that markets were pricing in an approximately 86.5% probability of a 25-basis-point Fed rate hike in September, up sharply from around 30% a week earlier. At the same time, the U.S. 10-year Treasury yield briefly approached 5%, reaching its highest level since 2023. Market disagreement over whether the Fed will raise rates in September has narrowed considerably, with attention now shifting toward whether further tightening could follow after the initial hike.
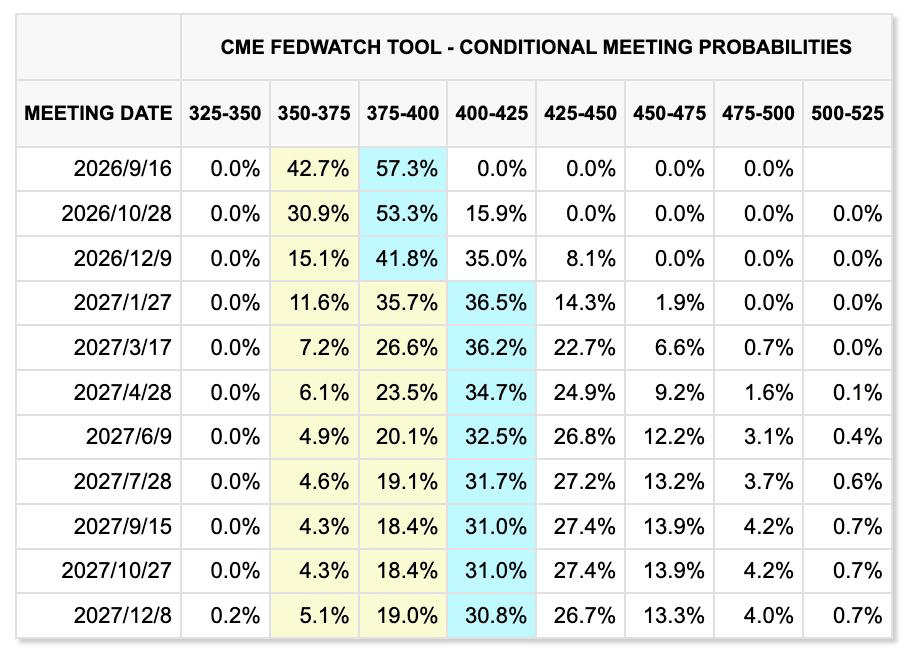
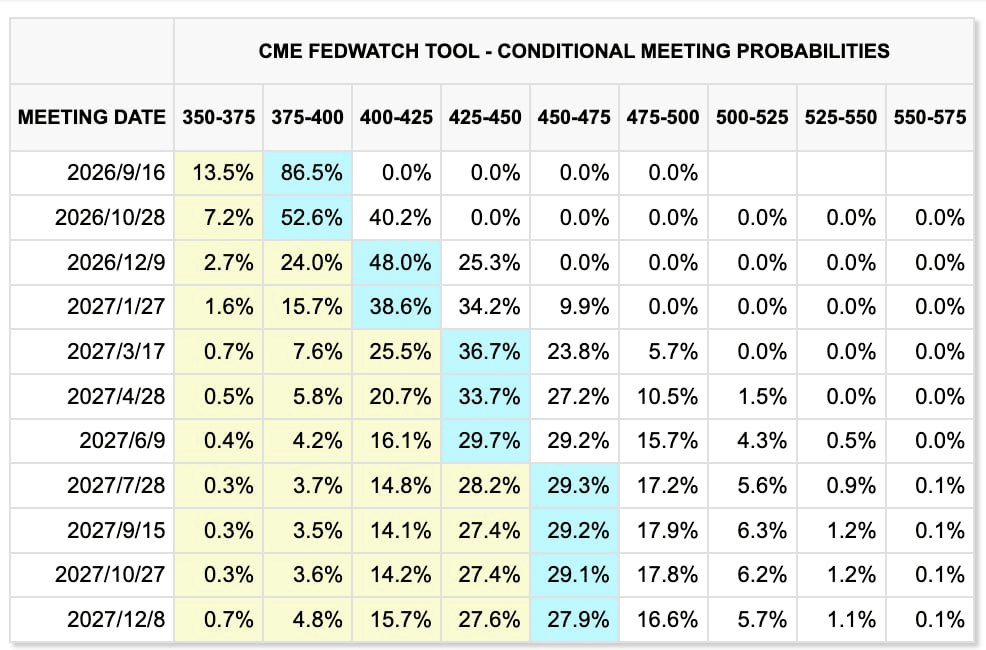
Changes in market pricing over the past two weeks (left: previous week; right: current week)
Source: CME FedWatch Tool
The case for consecutive rate hikes, however, is less clear than the case for a single September move. On one hand, U.S. nonfarm payrolls increased by approximately 162,000 in August, suggesting that the labor market has not weakened materially. On the other hand, wage growth does not show the typical signs of overheating, while U.S. federal debt has already exceeded $40 trillion and elevated long-term yields are themselves tightening financing conditions for businesses and households.
The substantial debt financing required for AI data-center expansion further amplifies the pressure that high interest rates place on technology companies’ cash flow and returns on capital expenditure. A September rate hike has therefore become a high-probability scenario, but whether the Fed enters a sustained tightening cycle will still depend on whether oil prices, employment, and core inflation remain persistently strong.
Middle East tensions are adding further inflationary pressure. Houthi forces attacked Saudi energy facilities, shipping through the Strait of Hormuz remained constrained, and Saudi Arabia’s East-West pipeline—used to bypass the Strait—was also shut following a drone attack, raising concerns over additional supply disruptions.
Brent crude gained approximately 8%–9% last week and briefly approached $110 per barrel, while WTI also moved back above $100. Talks between Iran and Gulf states over the Strait of Hormuz, originally scheduled for September 14, were subsequently postponed, suggesting that the geopolitical risk premium is unlikely to fade quickly in the near term.
Gold, meanwhile, continued to trade between elevated inflation risks and high real interest rates. Spot gold rebounded to around $4,363 per ounce on Friday but still fell approximately 1.5% over the week. Fiscal, geopolitical, and inflation risks continue to provide medium- to long-term support. However, with the 10-year Treasury yield approaching 5%, the opportunity cost of holding a non-yielding asset has risen materially, allowing short-term rate pressure to regain the upper hand.
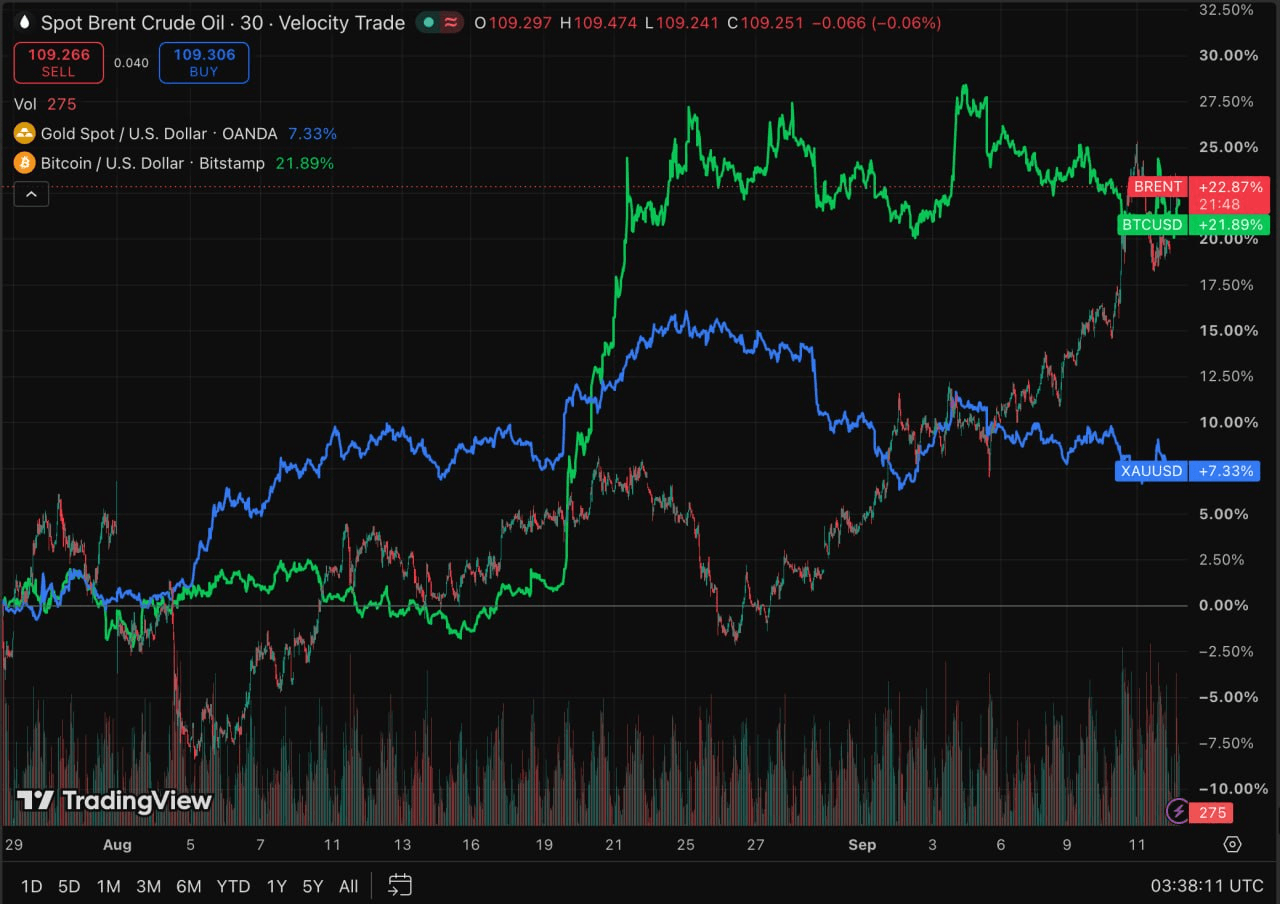
Source: TradingView
U.S. equities declined overall last week, with the S&P 500, Nasdaq, and Dow falling approximately 0.8%, 0.7%, and 1.6%, respectively. Rising oil prices and long-term yields weighed on valuations, but corporate earnings continued to provide support, preventing a broader sell-off across risk assets.
The AI sector also faced a new sentiment-driven risk. Over the weekend, leaders from Anthropic, OpenAI, and xAI unusually voiced support for slowing the pace of frontier-model development, raising concerns over the future growth rate of AI compute investment. At this stage, the impact remains primarily expectations-driven. Only if these signals translate into delayed model launches or lower capital-expenditure guidance would they materially affect demand for GPUs, HBM, servers, and related infrastructure. However, because Japanese and South Korean markets have relatively high exposure to the AI hardware supply chain, changes in policy and industry expectations could amplify short-term volatility in companies such as Samsung Electronics, SK Hynix, and SoftBank.
Crypto Assets and ETFs: BTC ETFs Return to Sustained Outflows While ETH Retains a Relative Funding Advantage
The crypto market came under pressure last week. BTC declined from around $80,000 at the beginning of the week to approximately $77,000, falling about 3%–4% over the week. ETH remained largely within the $2,450–$2,550 range and continued to outperform BTC on a relative basis.
The simultaneous rise in oil prices, inflation, and U.S. Treasury yields once again increased the effective dollar funding cost for crypto assets, although ETH’s relative resilience continued to be supported by ETF inflows.
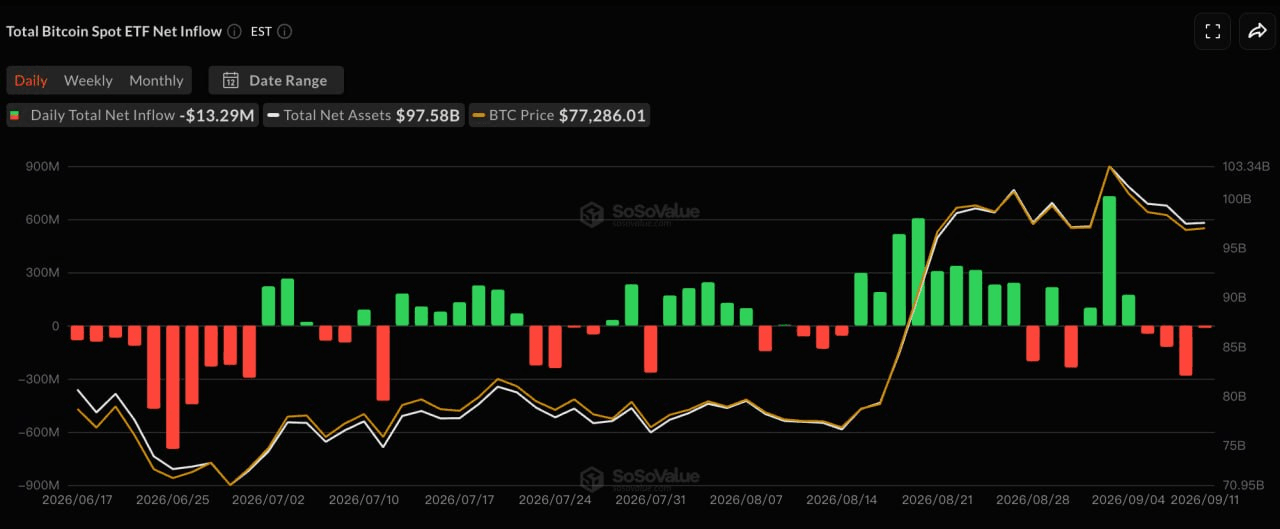
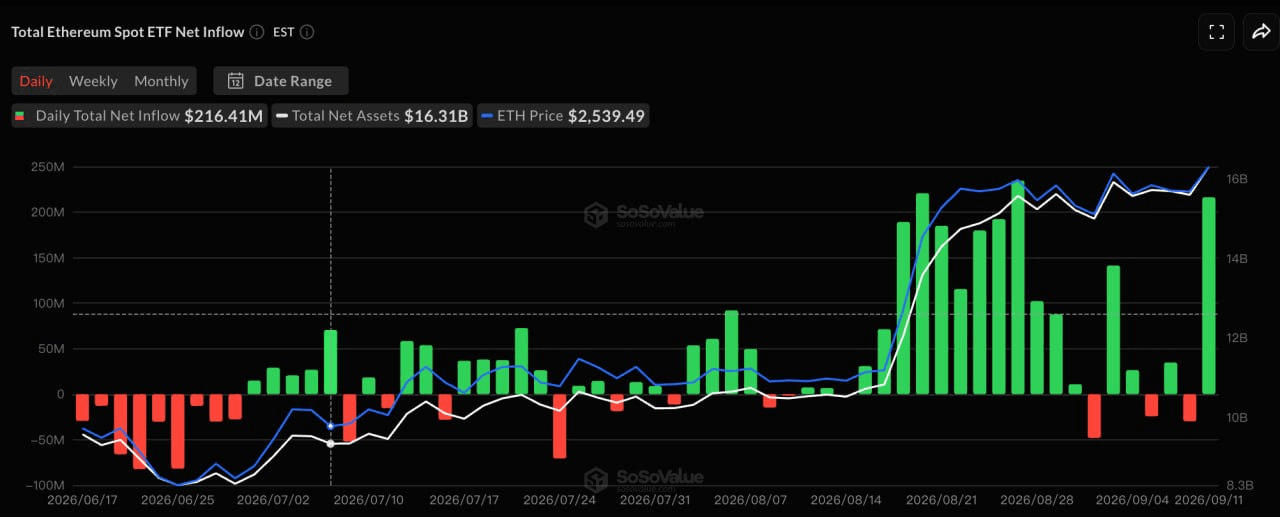
Source: SoSoValue
According to SoSoValue, with U.S. markets closed for Labor Day on September 7, U.S. spot BTC ETFs recorded approximately $463 million in net outflows across the four trading sessions from September 8 to September 11, ending a three-week streak of net inflows. ARKB and GBTC posted approximately $234 million and $129 million in net outflows, respectively, while IBIT and FBTC also turned negative.
ETH ETFs, by contrast, recorded approximately $197 million in net inflows over the same period, marking a fourth consecutive positive week. On September 11 alone, ETH ETFs saw approximately $216 million in net inflows, led primarily by BlackRock’s ETHA, which more than offset redemptions from earlier sessions.
The divergence between BTC and ETH ETF flows again suggests that institutional capital is not exiting the crypto market broadly, but is continuing to reallocate between major assets. Relative demand for ETH continues to improve, but total stablecoin supply has not expanded materially in parallel. The current environment therefore looks more like structural institutional rotation than the beginning of a broad new liquidity cycle across the crypto market.
Stablecoins: Total Market Capitalization Remains Flat as USDe Expands Against a Backdrop of Limited New Liquidity
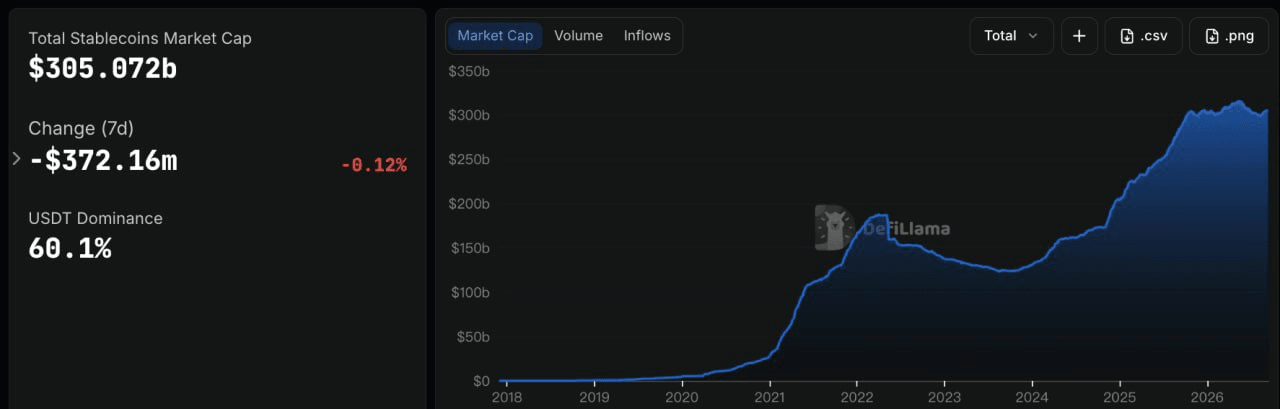
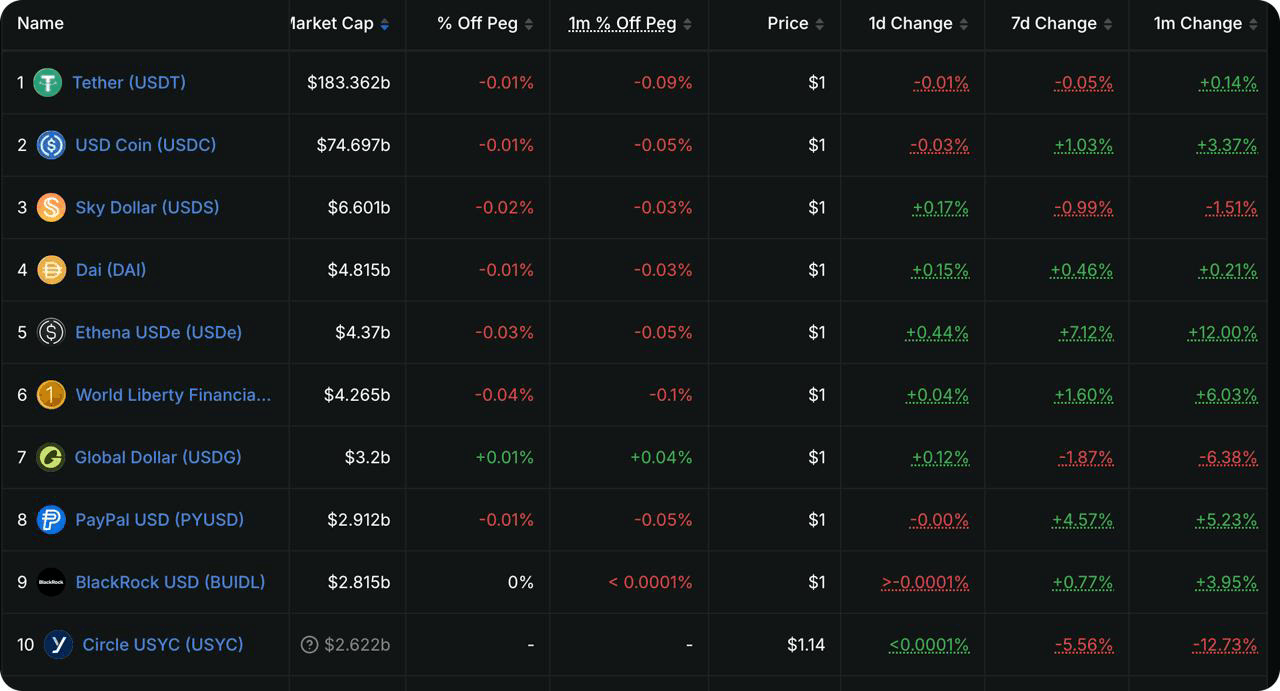
Source: DeFiLlama
DeFiLlama data showed that total stablecoin market capitalization stood at approximately $305.1 billion, broadly unchanged over the previous seven days with a slight decline of around 0.12%. USDT’s market share stood at around 60.1%. This suggests that the recent recovery in stablecoin supply has temporarily stalled, while changes in ETF flows have yet to translate into broad-based expansion in on-chain dollar liquidity.
Among the top 10 stablecoins, USDT was broadly unchanged, while USDC declined approximately 0.39% over the week. USDS and PYUSD fell by around 2.8% and 2.7%, respectively. The most notable change was USDe, which increased approximately 6.5% over the week to around $4.6 billion. USD1 and USDG also recorded modest growth. USDe’s expansion is consistent with a recovery in demand for yield-bearing products, with sUSDe-related yields still around 4.5%, encouraging some capital to increase exposure to yield-generating synthetic dollars.
Overall, the stablecoin market remains dominated by rotation between individual products rather than meaningful aggregate expansion. Yield-bearing products such as USDe are attracting incremental capital, while major stablecoins such as USDC have contracted slightly, indicating that the on-chain dollar liquidity base has not yet entered a new broad-based expansion phase.
Key Events to Watch This Week
Markets will focus on the Federal Reserve’s September policy meeting, the Bank of Japan’s policy decision, and developments around the Strait of Hormuz. With the probability of a September rate hike already priced above 80%, the FOMC’s guidance on the policy path for the remainder of the year may have a greater impact on risk assets than the rate increase itself.
-
September 16: The U.S. releases August retail sales. With rate-hike expectations rising sharply, the data will help assess whether higher oil prices and interest rates are beginning to weigh on consumer demand.
-
September 17: The Federal Reserve announces its FOMC rate decision, followed by a press conference from Warsh. Markets currently assign an approximately 86% probability to a 25-basis-point rate hike. Attention will shift from whether the Fed hikes to the dot plot, the possibility of additional tightening later in the year, and Warsh’s assessment of oil prices and long-term Treasury yields.
-
September 18: The Bank of Japan announces its policy decision. Markets broadly expect a 25-basis-point increase to 1.25%. If the BOJ signals faster policy normalization, a stronger yen and capital flows back into Japan could further disrupt global carry trades and create liquidity pressure for technology stocks and crypto assets.
-
Geopolitics: Talks between Iran and Gulf states over the Strait of Hormuz, originally scheduled for September 14, have been postponed with no new date announced. With crude oil again trading above $100 per barrel, progress on negotiations could directly affect global inflation expectations and subsequent Fed policy pricing.
Primary Market Fundraising Watch: Traditional Exchanges Deepen Tokenization Exposure While Stablecoin Payment Infrastructure Continues to Attract Capital
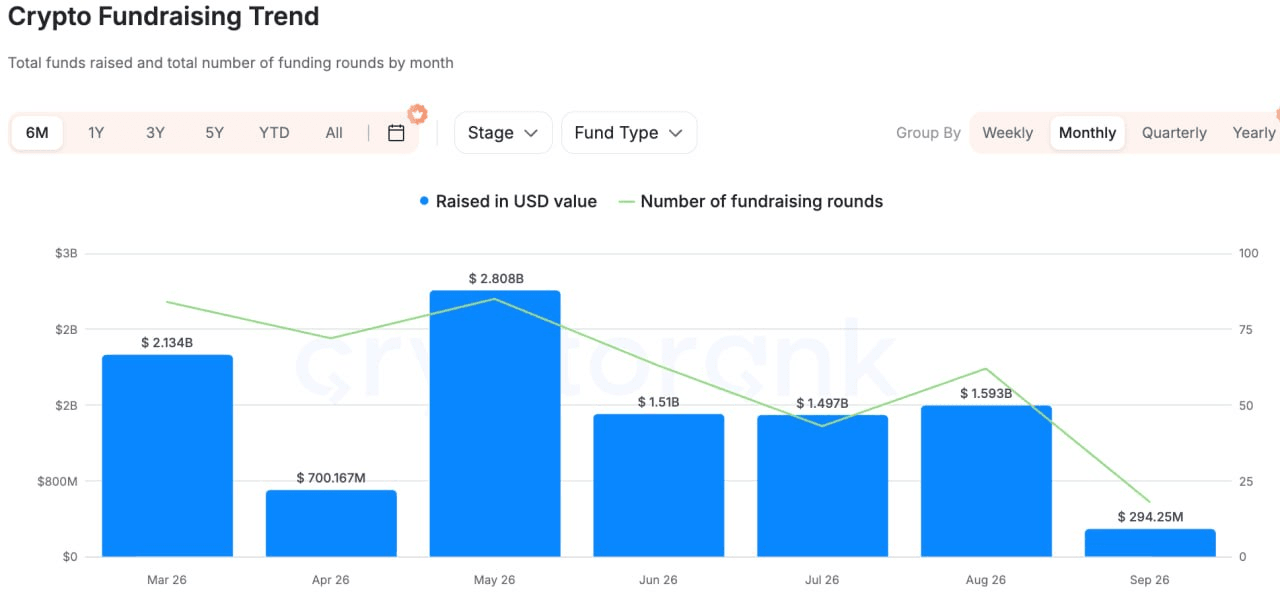
Source: CryptoRank
Based on broad funding data from CryptoRank, DeFiLlama, and other sources, private-market financing activity improved from the previous week, but capital remained concentrated in tokenization, stablecoin payments, and institutional infrastructure, rather than generalized on-chain applications.
One of the more representative transactions was Nasdaq Ventures’ $100 million strategic investment in Payward, the parent company of Kraken. The two sides plan to expand cooperation around trading, distribution, and post-trade infrastructure for tokenized equities, while Kraken will also adopt Nasdaq’s market-surveillance technology. The significance of the deal extends beyond a simple equity investment in a crypto exchange. It reflects a traditional securities exchange moving directly into tokenization infrastructure, suggesting that competition between TradFi and Crypto is shifting from whether assets move on-chain toward the integration of trading, liquidity, surveillance, and settlement systems.
In stablecoin payments, Latitude raised a $35 million Series A round, led by Oak HC/FT with participation from NEA, Coinbase Ventures, and others. The platform connects stablecoins with bank accounts, mobile wallets, and local payment networks across multiple jurisdictions. Its core value proposition lies in solving the “last mile” between on-chain dollars, real-world payments, and local-currency settlement.
In AI+Crypto, Agentum raised $7 million to build identity, custody, reputation, and on-chain settlement infrastructure for commercial activity conducted by AI agents. Compared with earlier, more generalized AI Agent narratives, capital is increasingly favoring infrastructure that addresses payment, trusted execution, and settlement.
Overall, the private market continues to reflect the same broader trend: traditional financial institutions are moving directly into tokenization trading infrastructure; stablecoin investment is shifting from issuance toward cross-border payments and local rails; and AI+Crypto capital is increasingly concentrated in underlying tools that support real transactions and settlement. General-purpose protocols without meaningful users, revenue, or distribution channels continue to face a more cautious financing environment.
Disclaimer This general market information, possibly from third-party, commercial, or sponsored sources, is not legal, compliance, financial, or investment advice, an offer, solicitation, or guarantee. We make no express or implied representations or warranties regarding its accuracy, completeness, or reliability, and disclaim liability for any resulting losses. Investments/trading are risky; past performance doesn't guarantee future results. Users should research, judge prudently, and take full responsibility. Please consult professional legal, tax, or financial advisors if necessary.