

Meta Stock Rises as Muse AI Tops ChatGPT and Gemini: Can the AI Agent Boom Last?
Meta’s AI Agent Surge Drives Stock Revaluation
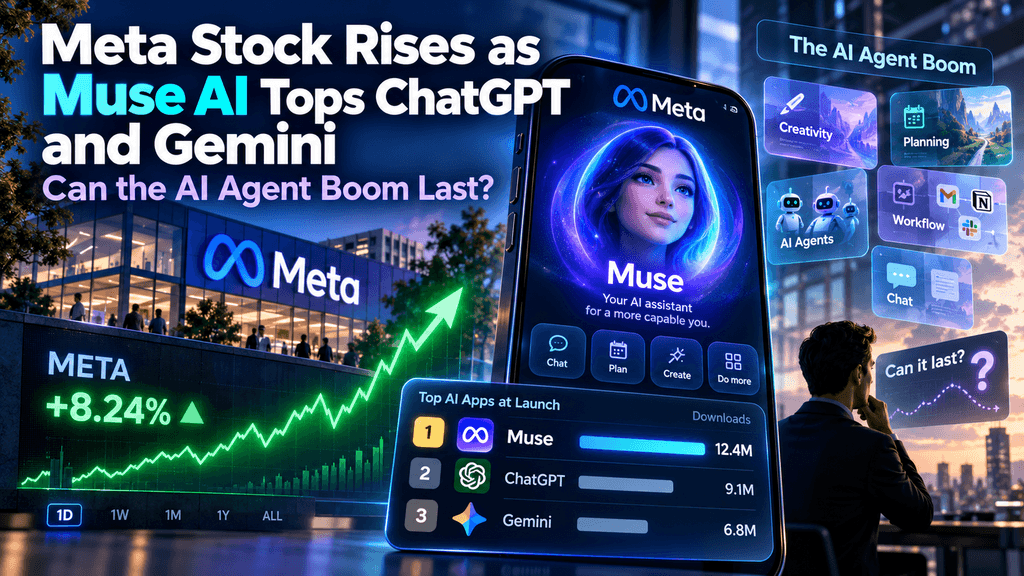
Meta Platforms shares have climbed sharply in recent weeks after the September 8, 2026, launch of Muse, its personal AI agent. The app quickly reached the top of free download charts in the United States and Canada, surpassing OpenAI’s ChatGPT, Google’s Gemini, and Anthropic’s Claude in early adoption metrics according to Sensor Tower and Apptopia data. Within roughly two weeks, Muse recorded between 2.5 million and 2.8 million downloads across iOS and Android in those markets, with daily peaks exceeding 200,000 installs. That traction translated into an 11 percent single-day gain for the stock on September 22 that added nearly $192 billion in market value, followed by a September rally of about 27 percent, the strongest monthly performance in years. Analysts from Wells Fargo, JPMorgan, and others raised price targets, citing Muse as evidence that Meta’s heavy AI investment is beginning to deliver consumer-scale results. The product positions itself as an autonomous assistant capable of booking travel, managing email, completing purchases via Stripe Link, and pursuing longer-term goals while running inside a dedicated secure virtual machine.
Early usage data and partnerships with Shopify and PayPal have reinforced the narrative that agentic AI is shifting from experimental chat interfaces toward practical task completion. Yet the speed of the rally has also prompted questions about valuation, monetization durability, competitive responses, and whether broad consumer trust will hold as agents gain deeper access to personal data and financial tools. Muse’s rapid chart dominance and the accompanying stock re-rating demonstrate that distribution advantages and free-tier accessibility can accelerate consumer AI agent adoption faster than pure model superiority alone, yet sustained value creation will depend on measurable conversion to paid tiers, reliable multi-step task completion, and clear evidence that the agent generates incremental revenue without eroding existing advertising or platform economics.
Muse Launch Metrics That Drove Immediate Investor Attention
Sensor Tower reported that Muse accumulated more than 2.5 million downloads in its first 13 days, while Apptopia data showed 1.8 million iOS downloads in the United States and Canada during a comparable 12-day window against ChatGPT’s earlier 1.3 million. Daily active users in the United States reached an estimated 642,000 at a similar early stage, far ahead of ChatGPT’s comparable figure of roughly 231,000. On September 19, the app set a U.S. daily download record of 264,000, and by mid-to-late September it held the number-one free position on Apple’s App Store, ahead of ChatGPT, Gemini, Claude, and even Meta’s own Meta AI application. These figures arrived against a backdrop of Meta’s prior multi-year capital expenditures on AI infrastructure, which had previously drawn skepticism about return timelines. The download velocity provided the first large-scale consumer signal that Meta could convert its existing user base, Facebook, Instagram, and WhatsApp, into agent adoption without requiring users to discover a new brand. Wells Fargo responded by lifting its price target from $640 to $796, aligning with prior record levels, while JPMorgan highlighted product-market fit and the free tier’s role in lowering trial barriers.
The data also showed Muse outpacing Claude’s 400,000 and Grok’s 200,000 downloads over the same early window, underscoring that agent utility and distribution outweighed pure reasoning benchmarks in initial consumer preference. Meta Chief AI Officer Alexandr Wang described Muse as the biggest consumer AI launch since ChatGPT, noting higher daily U.S. downloads than Threads, WhatsApp, or Facebook at comparable stages. The agent runs on the Muse Spark 1.3 model inside a per-user secure virtual machine that includes its own browser and persistent memory, allowing it to continue tasks after the user closes the app. Connectors for email, calendars, OpenTable, Ticketmaster, Spotify, Shopify, and Stripe Link enable concrete actions such as form-filling, reservation booking, and one-time virtual-card purchases covered by Stripe warranties. Free usage is metered; Power and Maximum subscriptions at $20 and $100 monthly raise token limits for heavier workloads. Availability remains limited to adults in the United States and Canada at launch, with WhatsApp integration and forthcoming support for Meta AI glasses expanding surface area. These design choices, persistent execution, payment rails, and Meta’s existing social graph explain why early metrics moved faster than many pure chatbot predecessors and why equity markets re-priced the stock so quickly.
Stock Performance Trajectory Since the September 8 Debut
From the Muse launch through late September, Meta shares advanced more than 20 percent, with the single Monday session of September 22 delivering an 11.3 percent rise to $741.25 and roughly $192 billion in added market capitalization. September as a whole produced a 27 percent gain, the strongest monthly advance since at least 2022 and among the best on record, bringing the company within striking distance of a $2 trillion valuation. The rally lifted the broader Nasdaq and Mag-Seven cohorts on several sessions, reflecting renewed confidence that consumer AI agents could become a meaningful revenue layer beyond advertising. By early October, the stock had moderated near the $720–$740 range yet remained substantially higher than pre-launch levels, with a 30-day return near 18 percent. Market capitalization hovered around $1.8 trillion, still below the absolute peak but well above the August trough. Volume spiked on the big up days, indicating institutional participation rather than purely retail momentum. Analysts noted that the move reversed earlier underperformance relative to peers and re-centered Meta in the AI narrative after periods of skepticism over capital intensity.
Price-target revisions followed the download data. Wells Fargo’s $796 target matched a prior closing high, while other firms moved estimates into the $800–$920 range, citing Muse’s potential annual revenue contribution measured in the tens of billions by the end of the decade. Truist estimated at least $28.5 billion by fiscal 2030 under optimistic conversion scenarios. The stock’s five consecutive weekly advances into late September underscored the durability of the initial re-rating, even as day-to-day volatility remained elevated. Relative to the S&P 500 and Nasdaq Composite, Meta’s September outperformance was pronounced, confirming that investors treated Muse as a company-specific catalyst rather than a broad market beta event. Subsequent sessions showed some profit-taking, yet the net gain from the launch date remained firmly intact into early October.
How Muse Differs in Architecture From Chat-Based Assistants
Muse operates as a persistent agent rather than a session-based chatbot. Each user receives a dedicated Muse Secure VM, an isolated Linux environment with browser, storage, and compute that continues working after the mobile or web interface is closed. The agent maintains memory across interactions, schedules recurring jobs, and seeks approval only for high-stakes actions such as outbound email or purchases. This design enables multi-step workflows that span hours or days, such as monitoring ticket availability, comparing prices, and completing a transaction once criteria are met. Meta emphasizes that credentials and tokens remain inside the user’s VM rather than central systems, with a Sentinel gatekeeper controlling external access. The free tier supports limited token usage while paid plans scale capacity dramatically, aligning cost recovery with heavier compute demand.
In contrast to pure conversational interfaces, Muse is marketed for goal-oriented delegation: users set objectives, and the agent proposes and executes plans. Early connectors cover productivity, commerce, and lifestyle services, with browser fallback for sites lacking public APIs. Stripe Link integration supplies single-use virtual cards, and Meta claims Muse is the first agent covered by Stripe’s warranties and return policies. These architectural choices address two historical barriers to agent adoption, security isolation and payment reliability, while leveraging Meta’s existing identity and messaging surfaces. Independent reviews and early user reports confirm that the agent can complete routine errands, though reliability still varies with task complexity and site design. The persistent VM model also raises the compute cost per active user relative to ephemeral chat sessions, a factor that will shape long-term unit economics.
Download and Engagement Comparisons With ChatGPT and Gemini
Apptopia and Sensor Tower data place Muse’s first-12-day U.S. and Canada iOS downloads at approximately 1.8 million versus ChatGPT’s 1.3 million over a comparable early mobile window. Cumulative U.S. and Canada totals reached 2.8 million across platforms within two weeks. Sensor Tower further recorded 730,000 downloads in the first five days and a peak daily figure of 264,000. By early October, Muse had approached 2 million mobile daily users according to Bank of America-cited Sensor Tower figures, while ChatGPT held 664 million mobile daily users and Gemini 151 million. ChatGPT’s absolute scale remains orders of magnitude larger because of its multi-year head start and global availability, yet Muse’s early velocity relative to ChatGPT’s own launch trajectory is the more relevant comparison for investor sentiment. Gemini’s monthly active users surpassed one billion in August 2026, illustrating that established platforms continue to expand even as new agents arrive.
The engagement differential in the first fortnight, Muse’s estimated 642,000 U.S. daily actives versus ChatGPT’s 231,000 at the same stage, suggests higher initial stickiness for task-oriented agents among users already inside Meta’s ecosystem. Muse’s free tier and WhatsApp surface reduce friction compared with subscription-gated agent modes elsewhere. At the same time, ChatGPT’s weekly active users reached 1.2 billion by late September, demonstrating that conversational AI retains massive habitual usage. Muse’s chart leadership therefore reflects a temporary lead in the narrow “personal agent” category rather than overall AI app dominance. Sustained success will require conversion of these early downloaders into recurring active users and, eventually, paid subscribers.
Analyst Revisions and Revenue Upside Scenarios
JPMorgan analysts described Muse as potentially the most widely used consumer AI application since ChatGPT, citing product-market fit, distribution, and the free tier. They raised the price target to $875. Truist projected at least $28.5 billion in annual revenue contribution by fiscal 2030. Raymond James estimated that servicing hundreds of thousands of daily downloads could cost up to $12 billion annually, while revenue could approach $50 billion under optimistic monetization. Evercore ISI framed Muse as a clearer catalyst than earlier metaverse investments. Bank of America reiterated a Buy rating with an $810 objective, noting the agent’s multi-step workflow capability. Median targets across 64 covering firms settled near $760, with the majority of ratings remaining Buy or higher.
These projections rest on assumptions about free-to-paid conversion, average revenue per user, and incremental take-rates on commerce transactions facilitated by the agent. A Motley Fool scenario illustrated that even a modest 5.5 percent conversion of one billion users at $25 monthly average would generate roughly $16.5 billion in subscription revenue, material against Meta’s trailing twelve-month revenue base above $228 billion. Transaction-based upside from shopping and booking commissions adds a second layer. Most analysts caution that realization depends on retention after the novelty period and on Meta’s ability to keep compute costs from outrunning monetization. The range of targets, from the mid-$700s to the mid-$900s, reflects differing degrees of confidence in these variables rather than disagreement about early download success.
Expected Responses From OpenAI and Google
OpenAI has advanced ChatGPT Work for multi-step office-style tasks and introduced higher-tier agent capabilities under paid plans, with some reporting of always-on “Dot” agents at the $100-plus level. Google continues to deepen Gemini Spark integration with Gmail, Docs, Calendar, and other Workspace surfaces, leveraging its existing productivity footprint. Anthropic’s Claude Cowork and xAI’s Grok remain more limited in consumer agent distribution. Muse’s free entry point and Meta’s social distribution currently differentiate it in the personal-errand category, while ChatGPT and Gemini retain advantages in research depth, document generation, and global reach. Early side-by-side tests of everyday prompts have produced mixed results, with Muse favored for tone and household practicality in some evaluations and ChatGPT preferred for operational realism in others.
Competitors are expected to accelerate agent features, expand free tiers where economics allow, and tighten ecosystem lock-in. Amazon’s reported blocking of Muse from its shopping site on credential-capture grounds illustrates one friction point that pure platform agents may face when operating across third-party properties. Apple’s potential entry via on-device or Siri-linked agents remains an overhang. The near-term competitive dynamic favors players with large existing user bases and clear payment or identity infrastructure, conditions Meta currently satisfies in the U.S. and Canadian markets. Longer-term differentiation will hinge on reliability, privacy controls, and the breadth of connectors rather than any single launch metric.
Monetization Pathways Beyond Advertising
Muse launches with no advertising inside the agent experience. Primary near-term monetization is subscription: free metered usage, Power at $20 monthly, and Maximum at $100 monthly. Meta has stated that most users should remain within free limits while power users fund incremental compute. Secondary pathways include commerce take-rates on purchases completed through Stripe Link and Shopify integrations, as well as potential future enterprise or small-business agent offerings. Muse for Small Business, announced later in September, adds connectors for Asana, QuickBooks, Slack, Notion, and Meta’s own advertising tools, positioning the agent as a productivity layer for independent operators. Analysts view transaction commissions and small-business subscriptions as higher-margin adjuncts to the consumer free tier.
Unit economics remain uncertain until retention and conversion data mature. High compute intensity of persistent VMs implies that free-tier users must either convert or generate sufficient advertising or commerce value elsewhere in the Meta ecosystem to justify ongoing costs. Partnerships already announced with Shopify for checkout and PayPal for discovery suggest that platform partners see near-term volume upside even if Meta’s direct take-rate is modest. The absence of in-agent advertising preserves user experience and differentiates Muse from ad-supported chat surfaces, yet it also removes a familiar Meta monetization lever in the early phases.
Privacy, Security, and Trust Considerations for Persistent Agents
Muse requires users to grant access to email, calendars, payment methods, and other services, raising the stakes relative to pure chat interfaces. Meta states that each Secure VM is isolated, that credentials stay inside the user’s environment, and that users retain approval rights for sensitive actions. Independent reporting has noted default data-collection practices for model improvement and the broader context of Meta’s recent multi-state settlement related to social-media harms. Early reviews have mixed assessments of actual task reliability versus the volume of data requested. Availability limited to adults in the United States and Canada reflects both regulatory caution and staged rollout strategy.
Trust will be tested as agents attempt more financial and identity-sensitive tasks. Stripe’s warranty coverage for Muse-initiated purchases provides one consumer-protection layer. Opt-out mechanisms and transparent logging of agent actions are marketed as control features. Sustained adoption beyond the initial download surge depends on users experiencing more successful completions than errors or privacy concerns. Competitors emphasizing on-device processing or stricter data isolation may compete on the trust dimension even if their distribution is narrower. Regulatory scrutiny of agentic systems that can initiate transactions is expected to intensify as usage scales.
Market Impacts for the AI Agent Category
Muse’s early success has lifted related equities such as Shopify, which rose more than 11 percent in the same week after announcing Muse checkout integration, and provided a modest lift to PayPal. The episode rekindled debate over which platforms will capture the value of agent-mediated commerce and which will face disintermediation. Investors have begun to differentiate between model providers, distribution platforms, and infrastructure suppliers that benefit from higher agent compute demand. CPU-related names saw secondary strength on the thesis that agentic workloads increase inference volume.
At the same time, some fund managers have reduced Meta exposure, citing return-on-invested-capital concerns even after the Muse rally, illustrating that not all capital views the current valuation as fully justified. The agent category remains nascent. Absolute daily-user figures for Muse remain a fraction of established chat applications, and global availability is still limited. Success metrics will evolve from downloads and chart position toward retention, task-completion rates, and revenue per active user. The September re-rating of Meta demonstrates that equity markets will reward visible consumer traction, yet the durability of that re-rating hinges on subsequent quarterly evidence that Muse is additive rather than merely substitutive of existing engagement.
Infrastructure and Capital-Expenditure Context Behind the Launch
Meta has guided 2026 capital expenditures, including finance-lease principal payments, into a $130–145 billion range, reflecting continued investment in AI training and inference capacity. Muse’s persistent VM architecture increases the importance of efficient inference economics. The company has hired additional leadership for enterprise platforms and expanded model APIs, signaling parallel tracks for consumer agents and developer or business monetization. Analysts note that distribution of Meta models via hyperscaler platforms could further amortize infrastructure costs. The scale of spending had previously weighed on sentiment; Muse provides the first clear consumer product that can be mapped against that outlay.
Whether Muse ultimately justifies the capital intensity will be measured over multiple years rather than weeks. Near-term stock performance has already incorporated optimistic scenarios. Subsequent earnings reports will need to show either rising subscription or commerce revenue attributable to agents or continued advertising growth that benefits from deeper user engagement. The Connect event in late September featured additional Muse capabilities, including avatar video chat and expanded business connectors, reinforcing the company’s commitment to iterative product development rather than a single-launch event.
Potential Hurdles That Could Limit the Current Rally
Early download leadership does not guarantee long-term retention. Novelty-driven installs often decline after the first month if task success rates disappoint or if competing agents improve rapidly. Geographic restrictions to the United States and Canada limit the total addressable market until broader rollout. Compute costs for always-on agents could pressure margins if free-tier usage grows faster than paid conversion. Competitive responses from OpenAI, Google, and potentially Apple could compress differentiation. Privacy incidents or high-profile agent errors involving financial transactions would test user confidence.
Some institutional holders have already cited incremental return-on-invested-capital concerns as a reason for reducing exposure even after the September gains. Valuation has expanded with the rally. Shares trade at elevated multiples relative to historical averages, embedding expectations of successful monetization. Any shortfall in conversion metrics or slower-than-expected international expansion could prompt multiple compressions. Amazon’s reported restrictions on Muse shopping illustrate platform-level friction that pure agents may encounter. These risks do not negate the early data, yet they frame the conditions under which the current stock premium can be sustained.
Longer-Term Outlook for Consumer AI Agents and Meta’s Position
If Muse sustains multi-million daily active users and converts a meaningful percentage to paid plans or commerce activity, it establishes Meta as a leading consumer agent platform alongside its advertising franchise. The combination of social distribution, messaging surfaces, payment partnerships, and persistent infrastructure creates a defensible starting position in the U.S. and Canadian markets. Expansion to additional countries, deeper hardware integration via AI glasses, and small-business tooling broaden the opportunity. Success would also validate the thesis that agent utility, rather than pure model leadership, drives mass adoption.
Failure to convert early interest into durable engagement would leave Meta with high infrastructure costs and limited incremental revenue, returning the narrative to capital intensity without corresponding returns. The next several quarters of download retention, subscription metrics, and any disclosed agent-related revenue will determine whether the September 2026 re-rating proves durable. For now, Muse has demonstrated that a well-distributed, free-to-try personal agent can capture consumer attention and investor capital faster than many expected, resetting expectations for the entire category.
🔥 Beyond the Headlines: What KuCoin 5.0 Means for You
Market news moves fast — but where you act on it matters just as much. This October, KuCoin launches KuCoin 5.0, transforming KuCoin into a rebuilt platform. Here's what actually changes for you:
-
One account for everything. Older platforms split your money across separate "spot," "margin," and "futures" accounts and expected you to understand why. KuCoin 5.0's unified account removes that entirely — deposit once, and everything is simply there (only available to VIPs for now).
-
Stocks, indices, and commodities. KuCoin 5.0 expands beyond crypto into global markets. When crypto chops sideways and equities rally (or the reverse), you rotate in minutes instead of opening a brokerage account and waiting days for fiat rails.
-
Real-world assets (RWA). Tokenized exposure to traditional assets like commodities, right inside your crypto account. One of the fastest-growing segments in global finance is no longer reserved for institutions — you access it from the same balance you trade with.
-
Earn while you learn. Not ready to trade? KCUSD lets your stablecoins earn daily, auto-compounding interest. The lowest-stress way to put your idle deposit to work for 4% yield.
-
An AI assistant in plain language. Ask questions, get market context, understand what you're looking at — built into the platform, no jargon required.
-
An app that doesn't overwhelm. Faster, cleaner, and consistent — intuitive from the first tap, not after a tutorial.
-
Safety you can check, not just trust. A MiCAR-licensed EU entity, Proof of Reserves you can verify yourself, and internationally certified security (SOC 2 Type II, ISO 27001:2022).
Create your account in minutes — and start on the platform built for where crypto is going, not where it's been.
FAQs
How quickly did Muse climb the App Store rankings after its September 8 launch?
Muse reached the number-one free position on the U.S. Apple App Store within approximately ten days of launch, according to multiple analytics firms. Sensor Tower data showed 730,000 downloads in the first five days and cumulative totals exceeding 2.5 million within two weeks across U.S. and Canadian stores. The speed of ascent outpaced the early trajectories of several prior AI apps and provided the primary catalyst for the subsequent equity-market reaction.
What are the current pricing tiers for Muse?
Muse offers a free tier with metered usage sufficient for most routine tasks according to Meta. Paid Power and Maximum plans are priced at $20 and $100 per month, respectively, unlocking substantially higher token limits for heavier or more continuous agent activity. The company has indicated that the majority of users are expected to remain on the free tier while power users cover incremental compute costs.
Is Muse available outside the United States and Canada?
At launch and through early October 2026, Muse remains limited to adult users in the United States and Canada on iOS, Android, web, and WhatsApp. Meta has signaled forthcoming support for Meta AI glasses and potential geographic expansion, but no firm international timelines have been disclosed in public statements.
How does Muse’s early download performance compare with ChatGPT’s launch?
In comparable first-12-day U.S. and Canadian iOS windows, Muse recorded approximately 1.8 million downloads against ChatGPT’s earlier 1.3 million, according to Apptopia. Absolute scale still favors ChatGPT because of its multi-year head start and global presence, yet Muse’s relative velocity and daily-active-user figures at the same stage were notably higher.
What revenue contribution do analysts expect from Muse?
Projections vary widely. Truist has cited a potential $28.5 billion annual run-rate by fiscal 2030 under optimistic scenarios. Other firms model subscription and commerce take-rate combinations that could add tens of billions over time, while stressing that conversion rates and retention remain unproven. Near-term contribution is expected to be modest relative to Meta’s existing advertising revenue base.
Does Muse contain advertising?
Meta has stated that Muse contains no advertising within the agent experience. Monetization currently centers on subscriptions and potential commerce commissions rather than ad inventory inside the agent interface.
Disclaimer: This content is for informational purposes only and does not constitute investment advice. Investments carry risk. Please do your own research (DYOR).