

Liquidity Deficit in Russia's Banking Sector: What's Behind Sberbank's Revised Forecast
Introduction
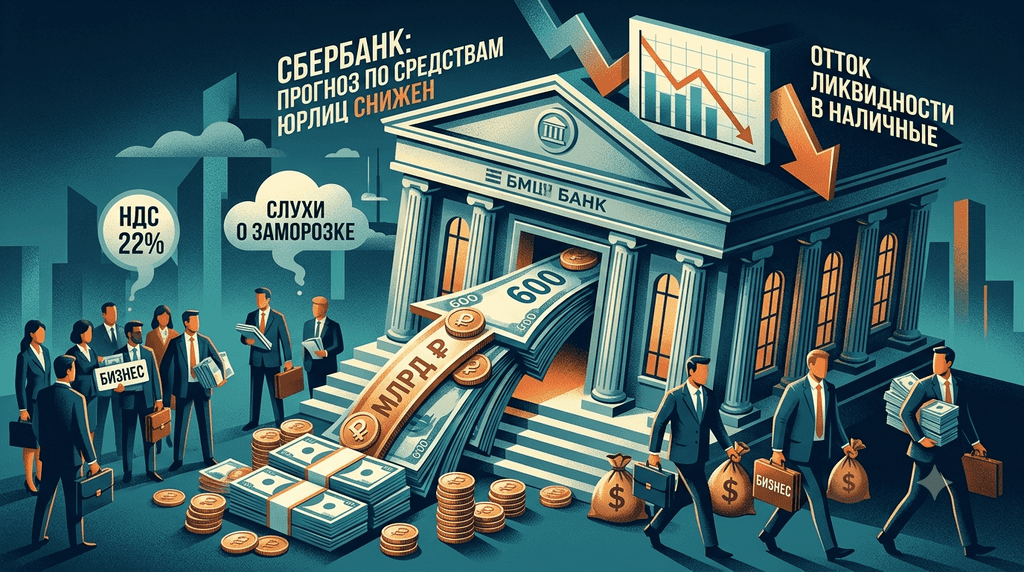
A cash outflow of nearly 600 billion rubles in a single month — that's what July 2026 looked like for Russia's banking system. Sberbank, the country's largest bank, has officially lowered its 2026 forecast for corporate client fund growth from 10–12% to 5–8%. The reason is a persistent trend of businesses shifting into cash, which has now been observed for two consecutive quarters and continues into the third. This was announced by Sberbank Deputy Chairman and CFO Taras Skvortsov during a conference call with analysts. Money market rates have already climbed above the Central Bank's key rate — a situation last seen at this scale only during the height of the 2020 pandemic. This article breaks down what is actually happening with liquidity in Russia's banking sector, the two factors driving the cash outflow, whether the problem extends across the entire market, and what conclusions investors might draw from the situation.
What Happened: Sberbank Revised Its Forecast for Corporate Funds
Sberbank officially cut its 2026 growth forecast for corporate client funds nearly in half — from 10–12% to 5–8%. The decision was announced during a conference call with analysts and confirmed by the bank's IFRS reporting.
According to that reporting, corporate client funds held in accounts and deposits at Sberbank stood at 14.65 trillion rubles at the end of June — almost 8% lower than at the start of the year. This is a substantial decline for a bank of this scale, given that Sberbank is the country's largest player, through which a significant share of corporate cash flows passes.
By comparison, retail deposits at the same bank grew by 3% over the same period, reaching 34.48 trillion rubles. This divergence is a key indicator: the problem is concentrated in the corporate segment, not among retail depositors, whose behavior remains stable and even shows moderate growth in savings.
| Indicator | Start of 2026 | End of June 2026 | Change |
| Corporate funds at Sberbank | ~15.9 trillion rubles | 14.65 trillion rubles | −8% |
| Retail deposits at Sberbank | ~33.5 trillion rubles | 34.48 trillion rubles | 0.03 |
| Cash in circulation (Russia-wide) | ~19.4 trillion rubles | 20.9 trillion rubles | +1.46 trillion rubles |
Taras Skvortsov described the current situation as atypical for the market: money market rates have moved above the Central Bank's key rate, and such a prolonged situation hasn't been seen in over a year. According to him, the bank does not rule out that this dynamic will persist going forward — meaning this is not a one-off spike but a structural shift in business behavior.
Why Businesses Are Moving Into Cash: Two Key Factors
Sberbank's CFO named two main reasons behind the large-scale outflow of funds from non-cash circulation. Both factors are working in parallel and reinforcing each other, which makes the situation harder to forecast.
The VAT Threshold Increase to 22%
Starting January 1, 2026, Russia raised its VAT threshold from 20% to 22%. According to Skvortsov, the Russian economy — small businesses in particular — has not yet fully adapted to the new tax conditions. This has pushed some entrepreneurs toward cash settlements as a way to optimize their tax burden and reduce costs during the transition period.
Such adjustment periods following tax changes are not unusual for developing economies: businesses need time to recalculate pricing models, payment logistics, and contractual terms with counterparties. Until this process is complete, a portion of transactions naturally shifts into the less transparent cash segment.
Rumors About Deposit Freezes
The second factor is statements by certain politicians about the need to freeze Russians' bank deposits. Although the Central Bank firmly denies such proposals every time and stresses they are not under consideration, some clients react nervously to these statements and move part of their savings into cash just in case.
Skvortsov specifically emphasized that these rumors have nothing to do with the Central Bank's own position, but that the problem is more of a communications issue — the market reacts to rhetoric faster than official denials can correct it. This is a textbook example of how the information environment can influence real financial flows faster than regulatory clarifications can catch up. Even in the absence of any official decision, the mere possibility of such measures being discussed publicly becomes a trigger for cautious depositor behavior.
How Widespread Is the Problem: Sector-Wide Data
Liquidity deficit is not an isolated problem at a single bank. Central Bank data confirms that the volume of cash in circulation has been actively growing since March 2026. As of July 1, the figure reached 20.9 trillion rubles, up 1.46 trillion rubles since the start of the year. In July, the outflow amounted to roughly 588 billion rubles — an absolute record for that month in the history of observations, as Skvortsov himself noted, adding that since the start of the year, factoring in the July estimate, cash in circulation has jumped by 2 trillion rubles.
VTB First Deputy Chairman Dmitry Pyanov had previously also reported that a "difficult situation" with ruble liquidity has been observed in the banking sector since mid-June. He linked this to higher liquidity utilization by the Finance Ministry as budget funds are spent, a reduction in supply at Federal Treasury auctions, and modifications to the Central Bank's money market operations. According to him, the RUONIA spread to the key rate has remained positive for an extended period, which directly indicates tension in the money market — a metric closely tracked by analysts as one of the main indicators of interbank market conditions.
Official Central Bank statistics confirm the systemic nature of the problem: in June, banks' demand for liquidity under market conditions rose to 4.7 trillion rubles, up from 4.1 trillion rubles in May. The regulator directly linked this to a 0.5 trillion ruble increase in cash in circulation — a pace exceeding levels seen in previous years. The fact that two of the country's largest banks — Sberbank and VTB — are reporting similar problems, combined with Central Bank data confirming rising aggregate liquidity demand across the sector, points to a systemic trend rather than an isolated case.
The Situation in Historical Context
Russia's economy has experienced comparable demand for cash only once in recent years — in the spring of 2020, at the peak of the COVID-19 pandemic, when uncertainty forced both businesses and the public to build up cash reserves. Back then, the spike in cash demand was short-lived and tied to the panic of the first weeks of lockdowns, after which the numbers quickly returned to normal as the situation stabilized.
The current situation differs in that it is stretched out over time: the outflow of funds has now been recorded for three consecutive quarters — from April through July — rather than appearing as a one-time shock. This fundamentally changes the risk assessment: while the banking system can absorb a short-term spike in cash demand using its own reserves, a sustained multi-month trend requires systemic solutions — either from the regulator through refinancing tools, or from businesses through adaptation to the new tax conditions. This is precisely why representatives of Sberbank and VTB are speaking out in tandem: the duration of the trend reduces the predictability of the money market for all participants, not just individual banks.
Similar episodes of liquidity deficit have occurred in other economies following sharp changes in tax or regulatory regimes: typically, the adjustment period lasts anywhere from several months to a year, after which cash flows gradually return to non-cash circulation as businesses build new operating models suited to the changed conditions.
What This Means for the Banking System and Depositors
The liquidity deficit is intensifying competition among banks for client funds and squeezing margins across the entire banking system. Skvortsov noted that starting in August, Sberbank's margin will also come under additional pressure from the payout of 2025 dividends — the bank will need to consolidate free client balances on its books, temporarily increasing the load on its balance sheet.
For ordinary depositors, it's important to understand that the lowered forecast concerns the inflow of corporate funds, not the stability of retail deposits, which, as the data shows, continue to grow. Nevertheless, rising money market rates could theoretically affect both deposit and lending terms in the coming months — banks facing a liquidity deficit tend to raise deposit rates to attract additional funding while simultaneously tightening lending conditions.
For businesses, in turn, the situation means potentially higher borrowing costs and tougher competition for banking services — especially for companies that depend on short-term financing for working capital. Small and medium-sized businesses, which have been hit hardest by the VAT increase, risk facing a double squeeze: a heavier tax burden combined with more expensive credit, if banks pass higher funding costs on through corporate lending rates.
Analysts also point out that a prolonged liquidity deficit can affect how quickly the Central Bank's monetary policy transmits through the economy: if money market rates persistently stay above the key rate, the effects of the regulator's key-rate decisions reach the real economy more slowly and less predictably than under balanced liquidity conditions.
Does This Threaten Financial Stability?
No emergency measures are needed right now — that's what Skvortsov stated directly, stressing that the bank is managing its liquidity issues using standard market tools. According to him, demand for cash of a comparable scale has been recorded in the Russian economy only once in recent years — during the acute phase of the COVID-19 pandemic in March 2020 — meaning the current situation is considered significant but manageable, not a crisis.
At the same time, Skvortsov underscored the importance of support from the Central Bank — through auctions and other short-term financing tools. Without such support, elevated money market rates could persist longer, further pressuring margins at both Sberbank and the banking system as a whole. Competition for client liabilities amid the shift into cash could also intensify further — which is exactly why the bank is already factoring this scenario into its own forecast for the second half of the year.
How Does the Liquidity Situation Affect Interest in Crypto and Trading on KuCoin?
Periods of instability in traditional financial markets often increase investor interest in diversifying portfolios through alternative asset classes, including crypto. This is a global tendency rather than something specific to the Russian market: fluctuations in interest rates, changes in tax regulation, and money market tension frequently become reasons for investors to look more broadly at crypto assets as a complementary — not a replacement — tool for managing savings.
On KuCoin, users can explore a wide range of tools — from spot trading in major cryptocurrencies to staking and futures contracts — alongside educational resources designed to help them understand the risks before they start trading. These tools allow investors to build their own capital management strategy based on their personal time horizon and risk tolerance.
It's important to stress that the crypto market is highly volatile, and any decision to trade should be based on independent risk analysis rather than as a reaction to news about the traditional banking sector. Registering on KuCoin provides access to market monitoring and portfolio management tools, but it is not financial advice and does not replace consultation with an independent financial advisor.
Join KuCoin 9th Anniversary Trading Campaign
KuCoin is celebrating its 9th anniversary with a special platform campaign filled with exclusive rewards, trading activities, and limited-time offers. Don’t miss the chance to participate and enjoy the benefits as the exchange marks nine years of growth and innovation. Visit the official campaign page now:
Conclusion
The liquidity deficit reported by Sberbank reflects a broader trend in the Russian economy: a significant shift of businesses into cash, driven by the VAT threshold increase to 22% and nervous reactions from some clients to rumors of a possible deposit freeze. The problem is systemic — VTB has confirmed a similar situation, and Central Bank data shows banks' liquidity demand rising from 4.1 to 4.7 trillion rubles in a single month.
At the same time, Sberbank emphasizes that it is handling the situation with standard tools and sees no need for emergency measures. The key factor going forward is the Central Bank's willingness to support the market through auctions and short-term financing instruments. For retail depositors, the situation currently poses no direct risk, since the main pressure is concentrated in the corporate client segment. Still, the situation serves as a reminder of how quickly tax changes and the information environment can affect business behavior and the money market as a whole — and of the importance of diversifying savings during periods of economic uncertainty.
Frequently Asked Questions
1. What is a liquidity deficit in the banking sector?
A liquidity deficit occurs when banks lack sufficient free funds to cover current obligations and market-rate operations, causing money market rates to rise above the Central Bank's key rate. This forces banks to compete more aggressively for funding and can raise the cost of borrowing across the economy.
2. Does Sberbank's situation threaten the safety of retail deposits?
No. Data shows retail deposits at Sberbank grew by 3% in the first half of 2026, reaching 34.48 trillion rubles — the problem is concentrated in corporate client funds, not retail deposits.
3. How is the VAT increase connected to the shift into cash?
Starting January 1, 2026, Russia's VAT threshold rose from 20% to 22%, and small businesses, according to Sberbank representatives, have not yet adapted to the new conditions — pushing some entrepreneurs toward cash transactions during the transition period.
4. What is Russia's Central Bank doing about the situation?
The Central Bank regularly denies rumors of deposit freezes and, according to bank representatives, is considering market support tools such as auctions and other forms of short-term financing, though final decisions on the scale and timing of any such support rest with the regulator.
5. Can crypto be used as an alternative to bank deposits during periods of instability?
Crypto can be considered as an additional portfolio diversification tool, but due to its high volatility it is not a direct substitute for a bank deposit and requires independent risk assessment before making any investment decisions.
Disclaimer : This material is provided for informational purposes only and does not constitute financial, investment, legal, or tax advice. Transactions involving cryptocurrencies and tokenized assets carry substantial risks — including price volatility, limited liquidity, counterparty exposure, and the potential for total loss of invested capital. Readers should conduct their own research and, where appropriate, consult a qualified professional before making any financial decisions.