

Strategy Briefly Surpasses Ford in Market Value as Bitcoin Treasury Bet Gains Attention
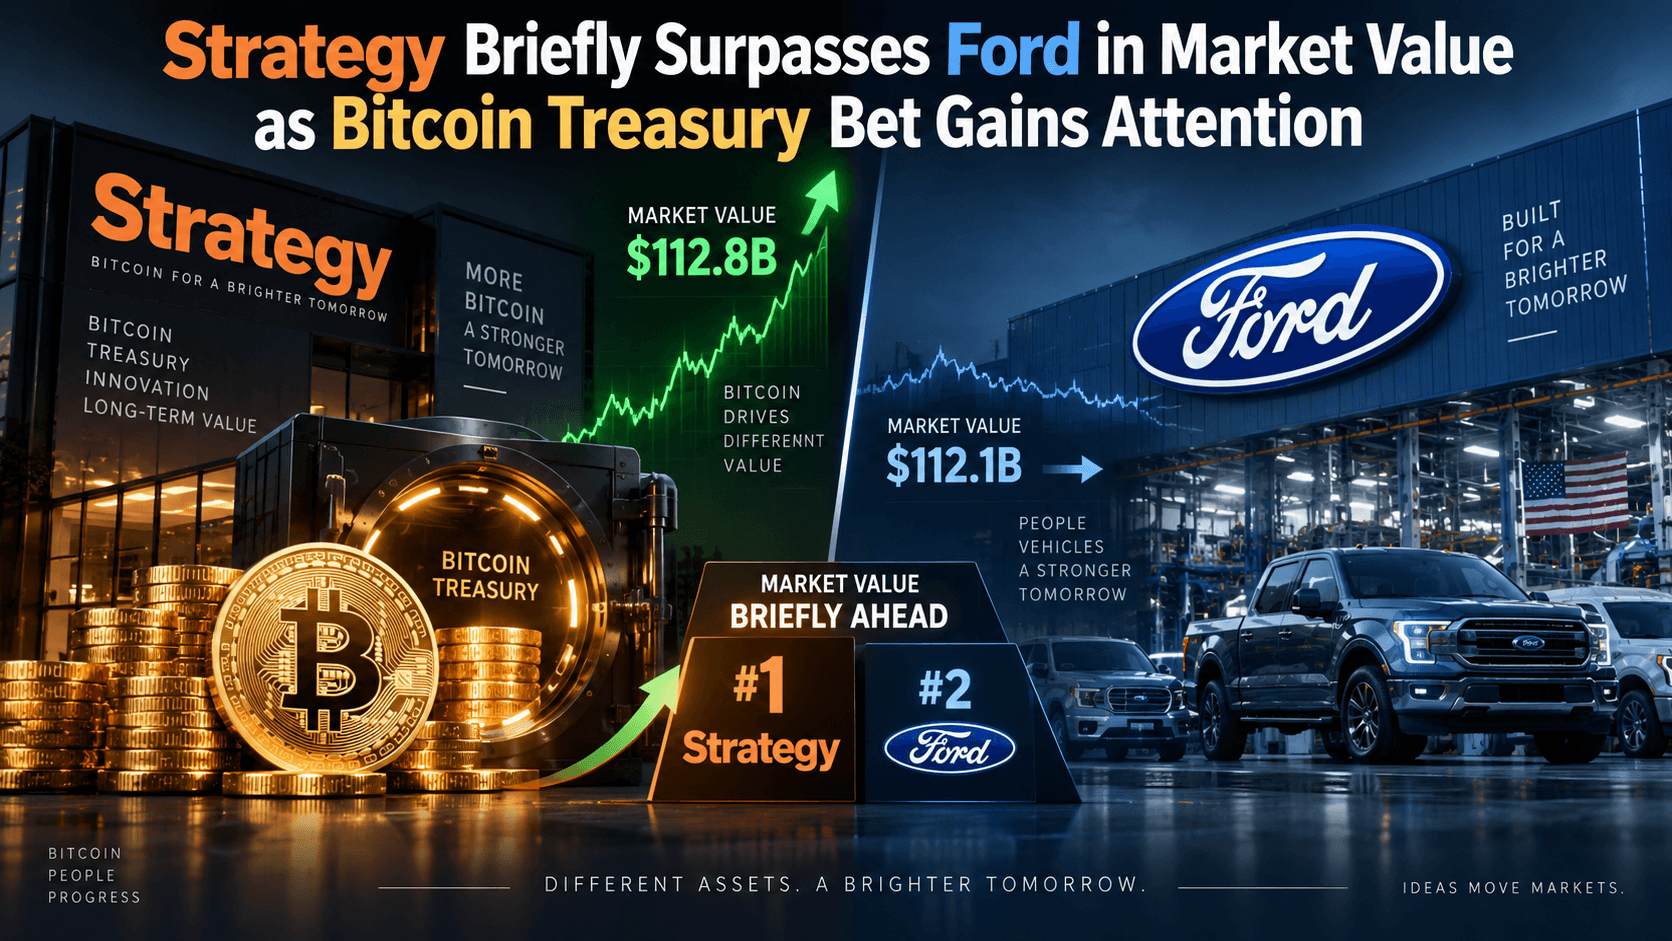
Strategy’s transformation from an enterprise software company into the world’s largest publicly traded Bitcoin treasury company reached a symbolic milestone in September 2026. A real-time BitcoinTreasuries.NET ranking cited by Binance News briefly placed Strategy’s market capitalization above Ford Motor, putting the company built around Michael Saylor’s Bitcoin strategy in roughly the same equity-value range as one of America’s best-known industrial businesses.
The comparison was short-lived, but that is almost beside the point. Strategy now holds 845,050 BTC, acquired for approximately $63.73 billion at an average price of $75,412 per Bitcoin. When Bitcoin was trading near $76,000 around the market-cap crossover, the entire position was only modestly above its cost basis. That raises a more interesting question than whether Strategy or Ford ranked higher on a particular afternoon: why is Wall Street willing to assign Ford-like equity value to a company whose financial strategy is increasingly built around Bitcoin and capital-market execution?
What Happened When Strategy Surpassed Ford?
The headline requires an important qualification. Strategy did not permanently become more valuable than Ford. A real-time market-cap ranking briefly showed MSTR ahead, but the companies were close enough that normal stock-price movements could quickly reverse the order. Ford shares closed September 15 at $13.50, down 2.6% for the session, while MSTR closed at $129.60, down 5.36%.
There is also a technical reason different websites may display significantly different market-cap estimates for Strategy. MSTR has used frequent at-the-market share issuance, so third-party databases can lag changes in shares outstanding. Strategy’s own August investor materials, for example, used roughly 394 million basic shares in one contemporaneous market-cap calculation, while some market-data services later continued using a lower share count. Strategy explicitly notes that its fully diluted and basic-share calculations can differ from outside market-cap estimates.
That makes “briefly surpassed Ford” the right framing. The real significance is not the exact ranking but the fact that the two common-equity valuations entered the same broad range.
How Much Bitcoin Does Strategy Own?
Strategy’s latest filing says it held 845,050 BTC as of September 13, 2026. The company paid about $63.73 billion for those coins, including fees and expenses, giving it an average acquisition cost of approximately $75,412 per BTC. It did not buy or sell Bitcoin during either of the first two full reporting weeks of September.
| Strategy Bitcoin Position | Latest Disclosed Figure |
| Bitcoin holdings | 845,050 BTC |
| Aggregate purchase cost | $63.73B |
| Average purchase price | $75,412 per BTC |
| Share of Bitcoin’s 21M maximum supply | About 4% |
At a Bitcoin price near $76,000, those holdings would be worth about $64.2 billion, only slightly above their aggregate acquisition cost. That makes the Ford comparison particularly striking. Strategy did not reach this valuation milestone because its Bitcoin reserve was sitting on tens of billions of dollars of unrealized profit. Instead, investors were valuing the corporate structure around that reserve: the financing platform, future Bitcoin accumulation potential, liquidity, capital allocation and residual upside available to MSTR common shareholders.
Why Does Wall Street Value MSTR Like a Bitcoin Company?
Strategy still operates a real enterprise software business. In the second quarter of 2026, software revenue reached $122.4 million, up 6.9% year over year. Subscription-services revenue rose 54% to roughly $62.9 million, reflecting the company’s continued migration toward cloud subscriptions.
But that operating business is now small relative to the scale of Strategy’s Bitcoin reserve and capital structure. Strategy itself describes the company as combining a Bitcoin treasury operation, a Digital Credit capital-markets platform and an enterprise analytics software business. Its investor materials say MSTR’s value remains dominated by Bitcoin and the capital structure even though software can still contribute technology, customer relationships and operating optionality.
That is why valuing MSTR with a traditional software revenue multiple misses much of the story. Investors increasingly treat the stock as a residual claim on Bitcoin assets plus the value—or potential cost—of Strategy’s ability to issue securities, finance additional Bitcoin exposure and actively manage a complicated balance sheet.
How Strategy’s Bitcoin Flywheel Works
It Is No Longer Just “Borrow Money and Buy Bitcoin”
The early version of Strategy’s Bitcoin strategy was relatively easy to understand: raise capital, acquire Bitcoin and hold it. The current model is much broader. Strategy can access common-stock ATM programs, convertible debt and several classes of perpetual preferred stock, while also maintaining dedicated U.S. dollar liquidity. Capital raised from those channels can be used to buy Bitcoin, support dividends and interest, refinance claims or repurchase securities.
Strategy describes this as a “Digital Credit engine.” In its August investor materials, management explained that issuing preferred or other fixed-income-like instruments can increase Bitcoin exposure per share when capital is raised at attractive terms and Bitcoin’s long-run return exceeds the effective cost of that financing. The company also explicitly warns that the same structure can destroy value if capital is raised on unattractive terms or Bitcoin returns fail to cover financing costs.
Strategy Is Becoming a More Active Capital Allocator
Recent activity shows how much the model has changed. Between August 24 and August 30, Strategy bought 4,603 BTC for approximately $369.7 million, paying an average of $80,318 per coin and lifting total holdings to 845,050 BTC. Yet during the next two reporting periods it did not buy additional Bitcoin. Instead, Strategy repurchased $176.3 million of STRC preferred stock, increased its Digital Credit repurchase authorization from $1 billion to $2 billion, and then spent another $139.3 million repurchasing STRC the following week.
That shift matters. Strategy is increasingly acting less like a company with a one-way mandate to buy as much Bitcoin as possible and more like a Bitcoin-focused capital allocator deciding whether the next dollar is best spent on BTC, liquidity, common shares or preferred securities.
Why Can Strategy’s Bitcoin Be Worth More Than MSTR?
A frequent mistake is to compare Strategy’s $60 billion-plus Bitcoin reserve directly with its common-stock market capitalization and conclude that MSTR must be trading at a discount to the Bitcoin it owns.
The problem is that MSTR common shareholders do not sit at the top of the capital structure. Strategy has billions of dollars of debt and multiple classes of preferred stock that rank ahead of the common shares. In an August 10 snapshot, Strategy reported approximately $6.75 billion of debt and $15.24 billion of preferred stock, alongside its Bitcoin and USD reserves. Strategy explicitly describes MSTR as the residual equity of the company and warns that common shareholders rank behind those senior claims.
What Does mNAV Mean for MSTR?
Strategy uses a supplemental metric called mNAV to compare MSTR’s market valuation with what it calls Net Bitcoin Value per share after specified senior claims. This is not traditional fund NAV and is not a liquidation value. Strategy’s own materials say the premium can reflect its capital-markets franchise, software, brand, liquidity, optionality and investor expectations—and that the premium can disappear or become negative.
That distinction is crucial. A headline such as “Strategy owns $64 billion of Bitcoin but has only a $50 billion market cap” does not prove the common stock is undervalued, because it ignores debt, preferred claims, future financing costs, other liabilities and dilution.
Why Does MSTR Move More Than Bitcoin?
MSTR is often described as a leveraged Bitcoin proxy, but Strategy itself cautions that it is not a spot Bitcoin ETF. MSTR shareholders have no direct redemption right over specific Bitcoin, and the stock’s return can diverge substantially from BTC because of debt, preferred dividends, share issuance, software performance, capital-market conditions and changes in mNAV.
The September 15 session illustrates the point. Bitcoin fell toward roughly $76,000 as crypto markets reacted to regulatory uncertainty and a difficult macro backdrop, while MSTR declined 5.36%. Crypto-linked equities were broadly weak following the Senate’s failure to advance the CLARITY Act, with Coinbase also falling sharply.
But there is no permanent multiplier such as “MSTR moves twice as much as Bitcoin.” When Bitcoin rises while mNAV expands and financing conditions improve, MSTR can significantly outperform. If Bitcoin declines while the market simultaneously compresses the valuation premium assigned to Strategy’s capital structure, the stock can underperform BTC. That reflexivity works in both directions.
Why the Ford Comparison Matters — and Why It Can Mislead
Ford and Strategy are almost opposites as businesses, which is exactly why the comparison attracted attention.
| Strategy | Ford |
| Bitcoin treasury, capital markets and software | Global automotive manufacturing and finance |
| Valuation highly sensitive to Bitcoin | Valuation tied to vehicle demand, margins and credit |
| Relatively asset-light operating business | Capital-intensive manufacturing network |
| Complex preferred/debt structure around BTC | Traditional industrial and finance balance sheet |
| High equity-market reflexivity | Cyclical operating-company valuation |
Ford had roughly 3.99 billion shares outstanding based on its latest regulatory filing, while its economic engine includes vehicle manufacturing, Ford Credit, factories, supply chains and global distribution. Strategy, by contrast, has built much of its financial identity around Bitcoin reserves and securities issuance.
So saying Strategy briefly had a higher market cap does not mean Strategy became a larger company by revenue, employees, production capacity or physical assets. Market capitalization measures the equity market’s value of the common shares. What the crossover shows is that investors were briefly willing to assign roughly comparable common-equity values to two radically different claims on future economic value.
Why the Timing Matters for MSTR
The milestone came at an unusual moment because September 15 was not a broad crypto euphoria session. Bitcoin fell, Strategy dropped more than 5%, and the U.S. Senate failed to advance the CLARITY Act. At the same time, markets were preparing for a Federal Reserve decision and the 10-year Treasury yield moved above 5%, a level not seen since 2007.
That means MSTR was confronting both crypto-specific risk and macroeconomic risk. Regulatory uncertainty can weigh on Bitcoin-related companies, while rising Treasury yields increase the opportunity cost of speculative assets and raise financing hurdles across capital markets. For Strategy specifically, higher rates can matter twice: they can pressure Bitcoin and risk appetite while also affecting the pricing investors demand from the company’s preferred and debt securities.
The brief Ford crossover therefore did not occur simply because Bitcoin was surging and speculative enthusiasm was at a peak. It happened because Strategy’s valuation had already moved into the same broad zone as Ford before a difficult risk-off session pushed MSTR back down.
What Does This Mean for Corporate Bitcoin Treasuries?
Strategy has demonstrated that a corporate Bitcoin strategy can evolve far beyond putting excess cash into BTC. Its model now combines a reserve asset, public equity, debt, perpetual preferred securities, dedicated liquidity and active capital allocation. Strategy’s August investor presentation described the company as seeking to use scale, liquidity and access to several financing channels to increase Bitcoin exposure per share over time.
That does not mean other companies can easily reproduce the strategy. Strategy benefits from unusually deep stock and options liquidity, a large existing Bitcoin reserve, years of public-market financing experience and an investor base that already understands MSTR as a Bitcoin-linked security. Smaller treasury companies may face much higher financing costs, thinner liquidity and less capacity to issue preferred securities on attractive terms.
The broader lesson is therefore not that every corporate treasury should copy Strategy. It is that public capital markets have now demonstrated a willingness to fund a business model in which Bitcoin treasury management itself becomes a major part of the company’s financial franchise.
What Should MSTR Investors Watch Next?
The first variable remains Bitcoin itself. Strategy’s average acquisition price is $75,412 per BTC, placing recent market prices unusually close to the company’s aggregate cost basis. A sustained move well above that level would expand the value of its reserve, while a major decline below it would again put much of the position into an unrealized loss.
But Bitcoin price alone is no longer enough. Investors also need to watch whether Strategy resumes major BTC purchases, whether it continues retiring STRC or other preferred securities, how much common stock it issues through ATM programs, and whether its USD Reserve remains sufficient to support preferred dividends and debt interest. As of early September, the company reported a $5.10 billion USD Reserve, while its capital framework explicitly allows issuance, repurchases and selective Bitcoin monetization depending on relative value and liquidity needs.
The longer-term test is straightforward but demanding: can Strategy increase Bitcoin-linked value per common share faster than financing costs, dilution and senior claims grow? That question matters much more than whether MSTR ranks above Ford on any particular trading day.
🔥 Beyond the Headlines: What KuCoin 5.0 Means for You
Market news moves fast — but where you act on it matters just as much. This October, KuCoin launches KuCoin 5.0, transforming KuCoin into a rebuilt platform. Here's what actually changes for you:
-
One account for everything. Older platforms split your money across separate "spot," "margin," and "futures" accounts and expected you to understand why. KuCoin 5.0's unified account removes that entirely — deposit once, and everything is simply there.
-
Stocks, indices, and commodities. KuCoin 5.0 expands beyond crypto into global markets. When crypto chops sideways and equities rally (or the reverse), you rotate in minutes instead of opening a brokerage account and waiting days for fiat rails.
-
Real-world assets (RWA). Tokenized exposure to traditional assets like commodities, right inside your crypto account. One of the fastest-growing segments in global finance is no longer reserved for institutions — you access it from the same balance you trade with.
-
Earn while you learn. Not ready to trade? KCUSD lets your stablecoins earn daily, auto-compounding interest. The lowest-stress way to put your idle deposit to work for 4% yield.
-
An AI assistant in plain language. Ask questions, get market context, understand what you're looking at — built into the platform, no jargon required.
-
An app that doesn't overwhelm. Faster, cleaner, and consistent — intuitive from the first tap, not after a tutorial.
-
Safety you can check, not just trust. A MiCAR-licensed EU entity, Proof of Reserves you can verify yourself, and internationally certified security (SOC 2 Type II, ISO 27001:2022).
Create your account in minutes — and start on the platform built for where crypto is going, not where it's been.
Conclusion
Strategy briefly surpassing Ford in market value is best viewed as a symbolic milestone rather than a permanent corporate ranking. The two companies operate entirely different businesses, and their market capitalizations can switch places quickly as their shares move.
What makes the event important is what it says about Strategy’s evolution. Bitcoin is no longer simply an asset sitting on the company’s balance sheet. It has become the foundation for a much broader capital-markets strategy involving common equity, preferred securities, debt, liquidity reserves and active capital allocation.
That structure can amplify value when Bitcoin performs well and financing remains attractive. It can also amplify losses when BTC falls, financing becomes expensive or MSTR’s valuation premium contracts.
The bigger story, therefore, is not whether Strategy remains worth more than Ford tomorrow. It is whether Wall Street continues to reward a public company whose core financial engine has been built around Bitcoin.
FAQs
Why Do Different Websites Show Different Market Caps for Strategy?
Strategy frequently issues shares through at-the-market programs, which means third-party databases can use different or outdated shares-outstanding figures. Strategy also reports basic and fully diluted share counts for different valuation purposes, so market-cap estimates may diverge depending on methodology and update timing.
Does Strategy Have a Limit on How Much Bitcoin It Can Own?
Bitcoin’s protocol does not impose a corporate ownership limit. Strategy’s practical ability to acquire additional BTC depends instead on financing availability, corporate policies, securities-market conditions, liquidity requirements and management’s capital-allocation decisions.
Can Strategy Sell Its Bitcoin?
Yes. Strategy’s current capital framework permits selective Bitcoin monetization for purposes such as supporting liquidity, meeting obligations or financing authorized security repurchases. The company nevertheless continues to describe long-term Bitcoin exposure as central to its treasury strategy.
What Is Strategy’s USD Reserve?
The USD Reserve is a dedicated pool of dollar liquidity intended primarily to support preferred-stock dividends and debt interest. Strategy reported a $5.10 billion USD Reserve as of early September, separate from additional USD Cash available for broader treasury and capital-management uses.
Does Briefly Passing Ford Affect MSTR’s Index Membership?
No. Passing another company in market capitalization does not automatically add Strategy to, remove it from or change its weight in a major index. Index providers use their own eligibility rules, float-adjusted market capitalization, rebalancing schedules and other criteria when determining membership.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Crypto assets can be highly volatile, and market conditions, token liquidity and project developments may change rapidly. Readers should conduct their own research and assess their risk tolerance before making financial decisions.