

Macroeconomic Outlook: How Federal Reserve Interest Rate Expectations and Big Tech Earnings Drive Crypto Risk Appetite
Introduction
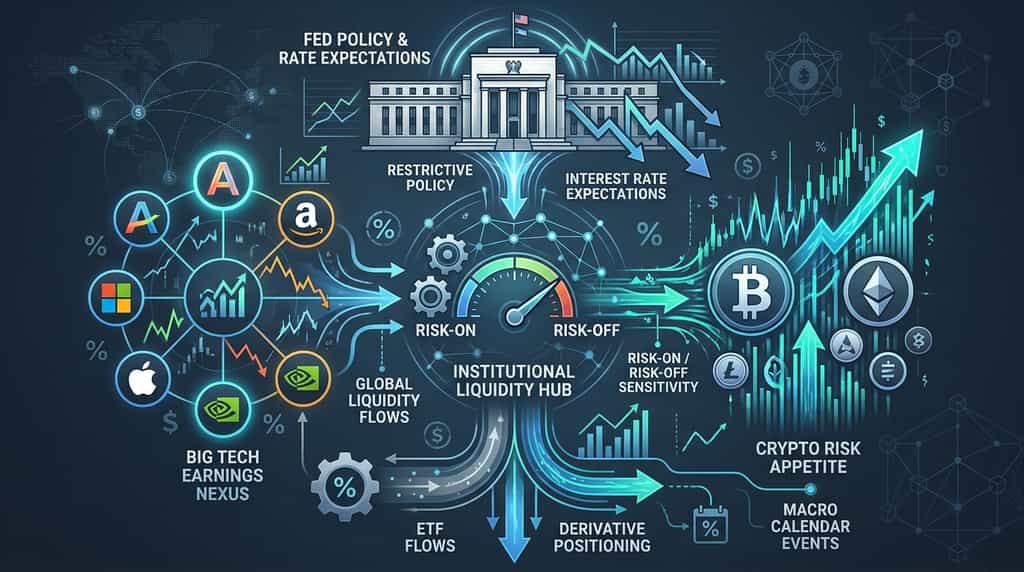
The macro environment dictates digital asset valuations, with crypto assets maintaining a high correlation to equity indices during periods of monetary policy shifts. According to the Federal Reserve's economic projections, ongoing adjustments to the federal funds target range directly influence institutional liquidity allocation, establishing a direct pipeline between traditional financial markets and cryptocurrency volatility. Understanding how macroeconomic policy decisions and corporate earnings performance intersect is essential for navigating market cycles.
Decoding Federal Reserve Interest Rate Policy and Crypto Liquidity
Federal Reserve interest rate decisions dictate global market liquidity, with lower rates expanding the money supply and driving capital into high-beta assets like cryptocurrencies. According to data from Trading Economics, the Federal Reserve maintained the federal funds target range at 3.75%–4.00%, following a 25 basis point rate increase that marked a persistent tightening posture. When borrowing costs remain elevated, institutional investors reallocate capital away from speculative digital assets toward fixed-income yields.
The primary transmission channel between central bank policy and crypto valuations is systemic liquidity. According to macroeconomic analyses published by S&P Global, periods of monetary contraction and balance sheet reduction historically coincide with compressed valuations across major digital assets. Conversely, anticipation of monetary easing lowers the opportunity cost of holding non-yielding assets, creating favorable conditions for sustained market expansions. Traders must continuously monitor FOMC statements and core inflation metrics to anticipate near-term liquidity shocks.
The Big Tech Earnings Nexus and Market Risk Appetite
Big Tech earnings performance functions as an immediate macro catalyst for cryptocurrency prices, with rolling correlations exceeding 0.60 between mega-cap equities and digital tokens. According to market analyses from eToro, combined trailing annual free cash flow for major technology conglomerates has faced scrutiny due to aggressive capital expenditures in artificial intelligence infrastructure and data centers. Because institutional asset managers group high-growth tech stocks and cryptocurrencies into the same risk-on asset class, earnings reports from industry leaders dictate cross-market sentiment.
When technology giants report earnings beats and robust forward guidance, systemic risk appetite expands, prompting capital inflows into spot exchange-traded funds and derivatives markets. Conversely, margin contraction or heavy capital expenditure guidance triggers immediate equity drawdowns, spilling over into accelerated crypto liquidations. According to on-chain derivatives data tracked across major institutional platforms, sudden risk-off moves in equities frequently trigger multi-million dollar redemptions in crypto ETFs, proving that digital assets remain highly sensitive to broader equity sentiment.
Institutional Plumbing: ETF Flows and Derivative Positioning
Institutional capital flows through regulated spot ETFs and derivatives exchanges create the modern bridge between macroeconomic data releases and digital asset price action. According to aggregated exchange data, single-day ETF redemptions spike during broader equity market corrections, demonstrating that institutional participants manage cross-asset risk uniformly. This institutionalization has fundamentally altered market mechanics, ensuring that macro shocks are priced into crypto order books faster than in previous market cycles.
Derivative market positioning reflects this heightened sensitivity, with options markets consistently pricing in elevated volatility premiums ahead of major FOMC meetings and corporate earnings announcements. Traders monitor funding rates, open interest shifts, and put-to-call skew ratios to evaluate whether leverage is overextended. When macroeconomic uncertainty climbs, negative skews indicate that institutional participants are actively bidding for downside protection, signaling a defensive stance across both equity and crypto portfolios.
Persistent inflation prints complicate monetary policy trajectories, forcing central banks to maintain restrictive stances that challenge crypto market momentum. According to the Federal Reserve Bank of New York’s Survey of Consumer Expectations, medium-term inflation expectations remain elevated, signaling that price pressures are sticky across core consumer sectors. Higher inflation prints diminish the likelihood of aggressive rate cuts, directly undermining the speculative expansion thesis for digital assets.
Concurrently, labor market resilience dictates the Federal Reserve’s timeline for policy pivots. A robust labor market gives central bankers the leeway to keep interest rates restrictive without triggering immediate economic contraction, keeping pressure on risk-on sectors. Investors evaluating macro risk must analyze employment reports alongside consumer price indices, as labor stability directly dictates how long monetary policy will remain a headwind for the cryptocurrency ecosystem.
Strategic Positioning Amid Macroeconomic Shifts
Navigating macro-driven markets requires disciplined risk management, strict adherence to technical support zones, and constant evaluation of cross-asset correlations. Because digital assets behave as high-beta extensions of global liquidity, portfolio construction must account for potential drawdowns triggered by traditional financial market corrections. Utilizing decentralized options, maintaining appropriate cash reserves, and monitoring institutional fund flows allow participants to protect capital during periods of heightened macroeconomic transition.
Long-term market resilience depends on the maturation of blockchain utility independent of central bank liquidity cycles, but short-term price discovery remains tethered to macro fundamentals. Traders who align their strategies with upcoming macroeconomic calendar events—such as FOMC rate decisions, Consumer Price Index releases, and mega-cap tech earnings disclosures—are better positioned to capitalize on volatility spikes. Success in modern crypto trading requires viewing blockchain assets not in isolation, but as an integral component of the global macroeconomic risk spectrum.
FAQs
How do changes in the US M2 money supply impact cryptocurrency valuations?
Changes in the M2 money supply directly alter the volume of fiat liquidity available for speculative investment. According to historical market studies by S&P Global, expansions in M2 resulting from quantitative easing or lower interest rates consistently precede major cryptocurrency bull runs, while monetary contraction restricts capital inflows and drives market corrections.
Why do institutional investors trade crypto and Big Tech stocks in tandem?
Institutional portfolio managers classify both high-growth technology equities and digital assets as high-beta, risk-on growth instruments. When macroeconomic conditions tighten or institutional risk models signal vulnerability, automated risk-management systems reduce exposure across both asset classes simultaneously.
What role do spot ETFs play in linking macro data to crypto prices?
Regulated spot ETFs provide institutional capital with direct access to digital assets, establishing automated channels for traditional finance capital allocation. Consequently, macro-driven outflows from traditional equity funds frequently trigger proportional redemptions in crypto ETFs, accelerating the transmission of macroeconomic shocks to blockchain markets.
How do producer and consumer price indices affect Federal Reserve policy decisions?
Producer and consumer price indices measure inflationary pressures across goods, services, and raw materials within the broader economy. When these indices print above consensus forecasts, the Federal Reserve responds by maintaining restrictive interest rates or signaling further policy tightening to combat inflation, which dampens risk appetite for digital assets.
Why are options volatility premiums important around earnings and FOMC releases?
Options volatility premiums quantify the degree of expected price movement priced in by institutional derivatives traders ahead of major high-impact events. Elevated volatility premiums indicate acute market uncertainty, allowing sophisticated traders to identify potential mispricings and manage directional risk effectively.
Disclaimer
This general market information, possibly from third-party, commercial, or sponsored sources, is provided for reference and educational purposes only and does not constitute financial or investment advice, an offer, solicitation, or guarantee. We disclaim liability for its accuracy, completeness, reliability, and any resulting losses. Investments/trading are risky; past performance doesn’t guarantee future results. Users should research, judge prudently, and take full responsibility. For further details, please consult KuCoin’s Terms of Use and Risk Disclosure.