

Cointelegraph Reportedly Seeks Buyer After Google SEO Penalty: What Went Wrong?
LAPTOP’s Extreme Launch Volatility and Forensic Findings
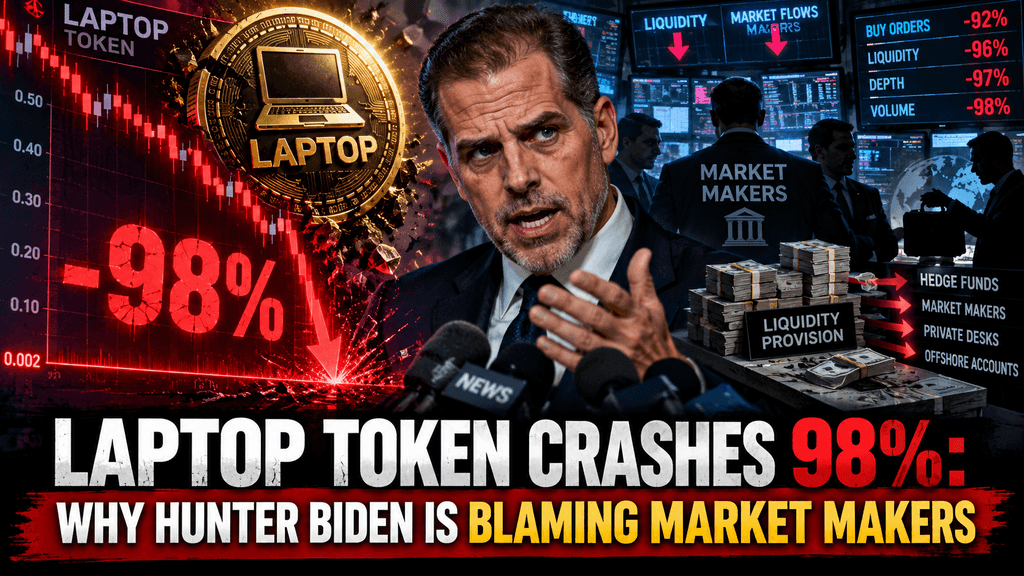
Hunter Biden’s LAPTOP token, launched on the Base network on September 9, 2026, experienced one of the most extreme price swings of any high-profile memecoin debut in recent memory. Opening near five cents, the token surged to roughly $317–$320 within two minutes before collapsing approximately 98% from that peak inside the first hour of trading. A month later, on October 7, Biden released findings from an independent forensic review conducted by Groom Lake. The report attributes the wild price action primarily to severely limited initial liquidity and the conduct of hired market makers rather than any founder selling.
Founders’ tokens remained unmoved, according to the analysis, while market-maker-linked activity generated substantial profits. This article examines the verified sequence of events, the forensic findings, trader outcomes, tokenomics design, and the broader implications for celebrity-backed token launches, drawing exclusively on contemporaneous reporting and on-chain data. The LAPTOP launch demonstrates how extreme liquidity scarcity can turn even a well-intentioned memecoin debut into a near-total wealth transfer from late buyers to early participants and market makers, regardless of founder lockups or public messaging.
Extreme Opening Liquidity Shortage Created Instant Manipulation Risk
The Groom Lake forensic review established that the primary liquidity pool for LAPTOP opened with fewer than 30,000 tokens, approximately 0.003% of the one-billion-token total supply, and only about $5,200 of the $500,000 that one market-maker wallet had received before launch. Across providers, the main pool held roughly $35,000–$36,000 in total value. Under those conditions, a purchase of just $6 moved the price by 5%, while an equivalent downward move required more than $7,000 in selling pressure. Groom Lake compared the imbalance against 668 other token launches and found none that approached the same asymmetry. The result was a quick ascent from the stated opening price of $0.05 to approximately $317–$320 in under two minutes, briefly implying fully diluted valuations in the hundreds of billions of dollars that had no relationship to actual depth.
Because the inventory of tokens available for sale near the market price was so thin, every early buy order compounded the upward move. Automated traders and retail participants chasing the celebrity narrative encountered virtually no resistance on the way up. The same scarcity then amplified the subsequent sell-off. Once the price reversed, the absence of meaningful buy-side liquidity forced sellers to accept progressively lower prices simply to exit. The forensic data therefore frames the entire opening sequence as a structural liquidity failure rather than a conventional demand-driven rally followed by profit-taking.
Market Maker Capital Deployment Fell Far Short of Stated Intent
According to the Groom Lake report and Biden’s accompanying statements, the project engaged two established market makers and supplied them with capital intended to support two-sided liquidity. One wallet linked to “Market Maker 1” received $500,000 yet deployed only about 1% of that sum, roughly $5,200, into the opening positions. The remaining capital was not used to deepen the pool at launch. Biden has publicly stated that the firm has offered no explanation for the limited deployment. The second market maker’s related activity generated more than $2.1 million in net USDC receipts, while Market Maker 1’s decentralized-exchange positions finished approximately $686,000 ahead, subject to any lender fees.
The decision to under-deploy capital at the precise moment of maximum expected demand created the conditions for the subsequent crash. Market makers are typically retained precisely to absorb volatility and maintain orderly markets. In this instance, the retained firms appear to have provided only a nominal presence at the open. The forensic timeline shows that 84 seconds after the price peak, Market Maker 1 withdrew funds from the pool while selling pressure was already intense, reducing near-market cash available to sellers from roughly $16,157 to zero. Traders attempting to exit thereafter had to drive the price substantially lower to locate any remaining liquidity.
Price Direction From Five Cents to Peak and 98% Collapse
LAPTOP began trading near $0.05 on Base. Within approximately 120 seconds, the price reached the $317–$320 range, according to DexScreener data cited in the Groom Lake review and contemporaneous coverage. That peak was followed by a roughly 98% decline within the first hour, leaving the token trading in the low single-digit dollars or below by the end of the opening session. Later snapshots placed the price near $0.75–$4 depending on the exact minute examined. By early October, the token had stabilized in a much lower range; as of October 8, 2026, it traded near $0.078 with a circulating market capitalization of approximately $27 million and a fully diluted valuation near $77 million.
The speed of both the ascent and the descent left little opportunity for ordinary participants to react. Early automated buyers captured the initial move; subsequent retail buyers entered near or after the peak and absorbed the bulk of the decline. Blockchain analytics firms, including Nansen and Bubblemaps, documented that the majority of unique buyers remained holding through the first day, converting what had been paper gains into substantial unrealized or realized losses. One wallet tracked by Nansen showed approximately $199,000 in total losses. The price action therefore functioned less as a free market discovery process and more as a quick transfer of value enabled by the liquidity vacuum.
Founder Tokens Remained Locked and Unmoved According to On-Chain Review
The Groom Lake analysis confirmed that the 300 million founder tokens, 30% of total supply, remained in a single wallet and had not been transferred as of the October 7 review date. Biden’s personal allocation is subject to a six-month lock followed by linear vesting over the subsequent two years. Public statements and the forensic report both emphasize that no team-linked selling occurred during the launch window. The project has repeatedly directed observers to the on-chain wallet for independent verification.
This lockup structure was presented as a deliberate contrast with earlier political memecoins that featured large unlocked insider allocations. Whether the design succeeded in aligning incentives is a separate question from the factual observation that the founder wallet did not contribute to the selling pressure on launch day. The absence of team dumps shifts analytical focus onto the market-making arrangements and the initial liquidity parameters, both of which were within the project’s control at the design stage.
Second Market Maker Activity Generated Additional Millions in Net Receipts
While Market Maker 1’s liquidity positions accounted for roughly $686,000 in gains, trades linked to a second market maker produced more than $2.1 million in net USDC receipts. Combined, the two firms extracted nearly $2.8–$2.9 million in the immediate aftermath of the launch, according to the forensic accounting. Neither firm is named in the publicly discussed portions of the Groom Lake report. Biden has called on the responsible market maker to repurchase the affected tokens and burn them, while acknowledging that he retains ultimate responsibility for the launch outcome.
These figures illustrate how market-making activity can become the dominant profit center in a poorly provisioned launch. In a liquid market, the same firms would typically earn spreads while facilitating orderly trading. In a near-empty pool, they effectively became the primary counterparties able to capture the extreme volatility they had helped create through under-deployment of capital. The report does not allege illegal conduct; it documents the economic result of the liquidity decisions made before and during the open.
Trader Loss Distribution Showed Broad Participation and Concentrated Damage
Analytics firms examining the first 24 hours recorded tens of thousands of unique buyers and a smaller number of sellers. Nansen data indicated more than 20,000 unique buyers against roughly 8,700 unique sellers, with the majority of buyers still holding at the time of the snapshot. Bubblemap analysis of approximately 15,000 wallets found that roughly 80% finished underwater, with most individual losses under $1,000, but a smaller cohort experiencing five- and six-figure drawdowns.
The distribution pattern is consistent with a classic thin-liquidity launch: a small number of early or automated participants extract liquidity, while the larger retail cohort that arrives after the initial spike absorbs the subsequent decline. Six-figure losses were documented in multiple wallets, confirming that the event was not limited to negligible retail speculation. The persistence of holdings after the crash also suggests that many participants either lacked the ability or the willingness to exit into the vanishing liquidity.
Tokenomics Design Included Airdrops, Prediction Markets, and Charity Allocations
LAPTOP was structured with a fixed one-billion-token supply. Roughly 30% was allocated to founders under the lock-and-vest schedule already described. Another 30% was tied to a series of real-world prediction events; tokens linked to unresolved or “no” outcomes were designated for charity. Community airdrops accounted for 20%, including a tranche aimed at wallets that had lost money on the earlier TRUMP memecoin. Remaining portions covered liquidity, foundation operations, and further charity. Biden positioned the design as an antidote to what he described as the grift of prior political tokens.
The prediction-market component and the TRUMP-loss airdrop generated considerable pre-launch attention. In practice, the sophisticated allocation structure did not protect the launch from the elementary liquidity failure that followed. The existence of locked founder tokens and charitable mechanisms did not alter the immediate market mechanics once the pool opened with almost no depth. Subsequent plans to burn most unclaimed airdrop tokens represent an attempt to reduce circulating supply after the fact.
Celebrity Memecoin Pattern Repeats Across Multiple High-Profile Debuts
LAPTOP joins a series of celebrity and political tokens that have exhibited quick spikes followed by severe drawdowns. The common structural features include limited initial liquidity relative to narrative-driven demand, heavy automated trading, and a retail cohort that enters after the first large moves. In each case, the theoretical fully diluted valuation at the peak bears little relation to the capital actually present in the pools. LAPTOP’s 98% first-hour decline from peak places it among the more extreme recent examples, yet the underlying mechanics are familiar.
The pattern raises persistent questions about the role of market makers in these launches. When firms are paid and capitalized to provide depth yet deploy only a fraction of that capital at the open, the resulting volatility becomes both predictable and extractable. Retail participants, attracted by the celebrity association, repeatedly supply the exit liquidity. The LAPTOP episode supplies unusually detailed forensic documentation of that sequence.
Independent Forensic Review Process and Its Limitations
Biden commissioned Groom Lake specifically to produce a transparent accounting after the launch attracted accusations of a rug pull. The firm examined every trade from the opening window, mapped liquidity positions, and compared the imbalance against hundreds of other launches. The resulting report supports the claim that founder tokens did not move and that market-maker under-deployment was the dominant mechanical cause of the price path.
Independent reviews of this type remain rare in the memecoin sector. Their value lies in the on-chain verifiability of the core claims. At the same time, the report does not name the market makers, does not compel any buy-back or burn, and does not address whether the original capital-deployment agreements contained enforceable depth requirements. The forensic exercise therefore clarifies the mechanics while leaving the commercial and contractual accountability questions open.
Current Market Position and Ongoing Project Commitments
As of early October 2026, the token trades near $0.078 with a circulating supply of approximately 350 million tokens and a market capitalization near $27 million. Liquidity has improved relative to the opening minutes yet remains modest by the standards of larger Base assets. Biden has stated that he will not abandon the project, that founder tokens remain locked, and that most unclaimed tokens from the first airdrop will be burned.
Whether these commitments restore confidence is an empirical question that will be answered by subsequent price action, holder retention, and any further burns or liquidity additions. The project continues to operate under the original tokenomics framework, including the prediction-market and charity components. Market participants evaluating the token must weigh the documented launch failure against the post-launch transparency effort and the absence of founder selling.
Practical Lessons for Evaluating Future Celebrity Token Launches
The LAPTOP episode supplies a clear checklist for future launches. First, examine the actual token inventory and dollar depth of the opening pool rather than the theoretical fully diluted valuation. Second, verify whether market makers have committed and deployed capital commensurate with expected demand. Third, confirm founder lockups on-chain rather than relying solely on statements. Fourth, treat any celebrity narrative as a demand catalyst that can amplify both upside and downside when liquidity is scarce.
These observations do not require speculation about intent. They follow directly from the measurable mechanics of automated market-maker pools. When the inventory of tokens available near the market price is a few tens of thousands against a billion-token supply, even modest order flow produces extreme price discovery. Participants who ignore that arithmetic repeatedly experience the same outcome.
What LAPTOP Means for Base’s Memecoin Liquidity Landscape
Base has hosted a large volume of memecoin activity. Extreme launches, such as the LAPTOP test, test the network’s capacity to handle sudden demand while highlighting the continued absence of standardized liquidity covenants for market makers. Projects that retain professional firms yet accept minimal opening depth create systemic risk for their own holders. The forensic transparency offered after the fact is useful for understanding what occurred; it does not retroactively restore capital lost by participants who bought into the thin pool.
Over time, repeated episodes of this type may encourage demand for clearer pre-launch disclosures of market-maker capital commitments and minimum depth thresholds. Until such practices become common, the combination of celebrity attention and sparse liquidity will continue to produce rapid wealth transfers of the kind documented in the Groom Lake review of LAPTOP.
🔥 Beyond the Headlines: What KuCoin 5.0 Means for You
Market news moves fast — but where you act on it matters just as much. This October, KuCoin launches KuCoin 5.0, transforming KuCoin into a rebuilt platform. Here's what actually changes for you:
-
One account for everything. Older platforms split your money across separate "spot," "margin," and "futures" accounts and expected you to understand why. KuCoin 5.0's unified account removes that entirely — deposit once, and everything is simply there (only available to VIPs for now).
-
Stocks, indices, and commodities. KuCoin 5.0 expands beyond crypto into global markets. When crypto chops sideways and equities rally (or the reverse), you rotate in minutes instead of opening a brokerage account and waiting days for fiat rails.
-
Real-world assets (RWA). Tokenized exposure to traditional assets like commodities, right inside your crypto account. One of the fastest-growing segments in global finance is no longer reserved for institutions — you access it from the same balance you trade with.
-
Earn while you learn. Not ready to trade? KCUSD lets your stablecoins earn daily, auto-compounding interest. The lowest-stress way to put your idle deposit to work for 4% yield.
-
An AI assistant in plain language. Ask questions, get market context, understand what you're looking at — built into the platform, no jargon required.
-
An app that doesn't overwhelm. Faster, cleaner, and consistent — intuitive from the first tap, not after a tutorial.
-
Safety you can check, not just trust. A MiCAR-licensed EU entity, Proof of Reserves you can verify yourself, and internationally certified security (SOC 2 Type II, ISO 27001:2022).
Create your account in minutes — and start on the platform built for where crypto is going, not where it's been.
FAQs
What exactly did the Groom Lake report conclude about the cause of the crash?
The report concluded that the primary liquidity pool opened with fewer than 30,000 LAPTOP tokens and only a few thousand dollars of the capital that had been provided to one market maker. That scarcity allowed small buy orders to drive the price from five cents to roughly $317 in under two minutes. Eighty-four seconds after the peak, the same market maker withdrew funds, eliminating near-price liquidity for sellers and forcing the subsequent 98% decline. Founder tokens were confirmed unmoved.
Did Hunter Biden or the founding team sell tokens during the launch?
On-chain data examined by Groom Lake shows that the 300 million founder tokens remained in a single wallet and had not been transferred as of the October 7 review. Biden’s personal allocation is locked for six months and then vests over two years. No team-linked selling was identified in the launch window.
How much did the market makers reportedly profit?
Market Maker 1’s decentralized-exchange positions finished approximately $686,000 ahead. Trading linked to Market Maker 2 generated more than $2.1 million in net receipts. Combined extraction approached $2.8–$2.9 million, according to the forensic accounting released with Biden’s statements.
What is the current price and market capitalization of LAPTOP?
As of October 8, 2026, LAPTOP traded near $0.078 with a circulating market capitalization of roughly $27 million and a fully diluted valuation near $77 million. Circulating supply stood at approximately 350 million tokens out of a maximum near one billion.
Were there significant trader losses beyond the overall price decline?
Yes. Analytics coverage documented that approximately 80% of examined wallets finished underwater. Multiple individual wallets recorded six-figure losses, including one tracked by Nansen at roughly $199,000. The majority of buyers had not sold by the end of the first day, converting temporary paper gains into sustained drawdowns.
What steps has the project announced after the forensic review?
Biden has stated that he will not leave the project, that founder tokens remain locked under the original schedule, and that most unclaimed tokens from the first airdrop (representing 10% of supply) will be burned. He has also publicly called on the responsible market maker to repurchase and burn tokens, while accepting personal responsibility for the launch outcome.
Disclaimer: This content is for informational purposes only and does not constitute investment advice. Cryptocurrency investments carry risk. Please do your own research (DYOR).