

GENIUS Act Final Rules: Can Stablecoin Issuers Pay Interest or Offer Rewards?
Introduction
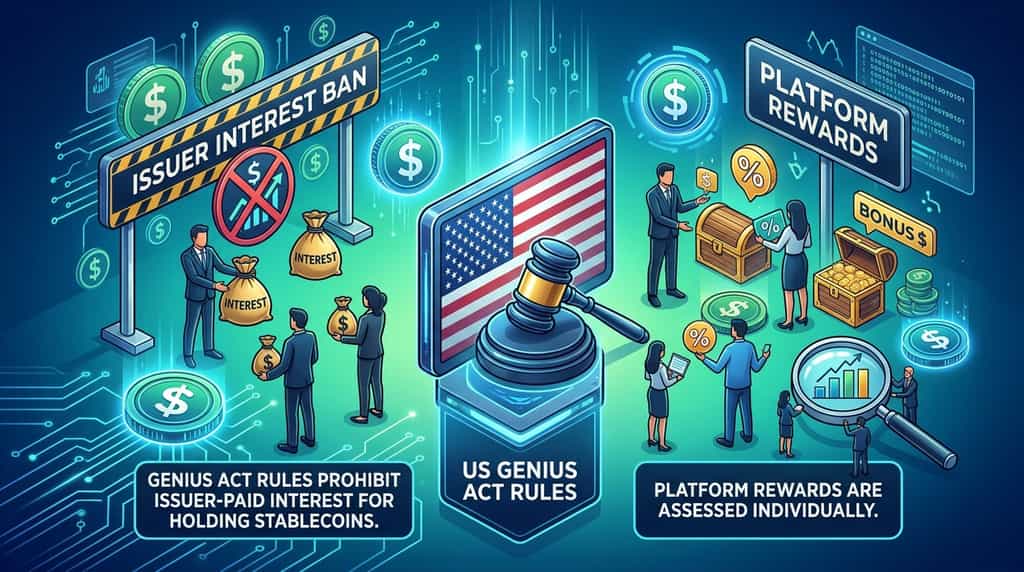
Can stablecoin holders still earn rewards under the United States' new stablecoin rules? The Office of the Comptroller of the Currency (OCC) issued its final GENIUS Act regulations on October 21, 2026, confirming that permitted payment stablecoin issuers cannot pay holders interest or yield solely for holding, using, or retaining their stablecoins. However, the rules do not automatically prohibit every rewards program operated by a separate crypto platform. Such arrangements may be assessed individually to determine whether they comply with the law.
The final rule implements the Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act, establishing requirements for payment stablecoin reserves, redemptions, risk management, supervision, and related activities. According to the OCC's official announcement, the rule takes effect on January 18, 2027.
For stablecoin users, exchanges, and issuers, the distinction between issuer-paid interest and platform-provided rewards is central to understanding the new framework. The rules could reshape stablecoin business models, competition for customer funds, and the role of stablecoins in the broader digital asset market.
What Does the Final GENIUS Act Rule Say About Stablecoin Interest?
The final rule confirms that covered payment stablecoin issuers cannot pay interest or yield to holders solely because they hold, use, or retain the stablecoin. This restriction applies whether the payment takes the form of cash, tokens, or other consideration. The statutory prohibition is established by Section 4(a)(11) of the GENIUS Act, enacted on July 18, 2025.
According to the official text of the GENIUS Act, the restriction applies to permitted payment stablecoin issuers and qualifying foreign payment stablecoin issuers. The law targets payments tied solely to stablecoin ownership or retention, rather than every possible commercial benefit associated with using a stablecoin.
The distinction matters because stablecoin issuers can generate revenue from the assets backing their tokens. For example, an issuer may hold permitted reserve assets, including short-term government securities and qualifying deposits, and earn income from those holdings. Under the law, the issuer cannot simply distribute interest to stablecoin holders because they keep the tokens in their wallets.
The rule does not mean that stablecoins themselves are prohibited or that users can no longer hold them for payments, transfers, or trading. Instead, it establishes boundaries around how covered issuers can compensate holders. Issuers must structure their products and business relationships within the applicable legal requirements, while users need to distinguish between the stablecoin itself and separate services that may offer rewards.
Can Crypto Exchanges Still Offer Stablecoin Rewards?
Crypto platforms may still be able to offer certain stablecoin rewards, but the final rule does not provide blanket approval for every program. The key question is whether a reward is genuinely a separate platform benefit or whether the arrangement effectively constitutes a prohibited payment by the issuer for holding, using, or retaining a payment stablecoin.
The OCC's final rule is notable because it does not retain the proposed presumption that certain third-party arrangements would automatically be treated as prohibited issuer payments. Instead, the agency can assess arrangements individually and take action where the facts indicate that a program violates the statutory restriction. The final rule therefore leaves room for legitimate commercial arrangements while preserving regulatory scrutiny.
For example, consider a crypto platform that offers a promotional benefit to eligible customers who use its services. The legal analysis would depend on the program's actual design, the source of the benefit, the agreements between the platform and issuer, and whether the arrangement is tied to simply holding the stablecoin. A program does not become permissible merely because a third party distributes the payment.
The same distinction applies to rewards paid in tokens rather than cash. The GENIUS Act expressly covers interest or yield provided in cash, tokens, or other consideration when the payment is solely connected to holding, using, or retaining the stablecoin. Changing the form of the benefit does not automatically change its legal character.
Accordingly, users should not assume that every existing rewards program will continue unchanged after the rules take effect. Platforms may revise eligibility requirements, reward rates, product terms, or geographic availability as they assess their obligations. Users should consult the terms published by the relevant provider rather than treating the existence of a rewards product as proof of regulatory approval.
How Does the Stablecoin Interest Ban Affect Issuers and Crypto Platforms?
The restriction could influence how stablecoin issuers compete, how platforms design customer incentives, and how users choose where to hold digital dollars. Its commercial impact will depend on the distinction between issuer revenue, platform revenue, and the benefits offered to customers.
For issuers, the restriction limits the ability to compete directly by paying holders a yield simply for retaining tokens. Issuers may still compete through payment utility, redemption arrangements, transparency, reserve management, and integration with digital asset services, subject to the law's other requirements. A stablecoin's commercial appeal may therefore depend more heavily on its usability and the quality of its supporting infrastructure.
For exchanges and other service providers, the rules create a need to review reward structures and contractual relationships. A platform that offers rewards independently may face a different analysis from an issuer that pays holders directly, but labels alone will not settle the question. Regulators can consider the substance of an arrangement and whether the economic benefit is effectively an issuer payment connected to holding stablecoins.
For users, the most immediate practical effect may be uncertainty about the future of particular rewards programs. Some providers may retain eligible offers, while others may modify or discontinue products. Reward availability can also depend on customer location, account status, product terms, and the platform's own regulatory obligations.
The final rule also establishes broader standards for reserves and redemptions. These provisions matter because confidence in a payment stablecoin depends not only on incentives but also on whether it is adequately backed and can be redeemed under the applicable framework. The OCC's final regulations address these issues alongside risk management, reporting, and supervision, making the GENIUS Act implementation a broader change to stablecoin oversight rather than an interest-only measure.
What Are the Main Risks and Uncertainties Under the New Rules?
The main uncertainty is how regulators will assess specific rewards arrangements and how individual providers will respond before the January 18, 2027 effective date. The final rule establishes the framework, but the details of a program's design and operation can determine whether it complies.
One risk is that users may confuse the statutory prohibition with a universal ban on every form of stablecoin reward. That interpretation is too broad. The law targets issuer payments tied solely to holding, using, or retaining covered payment stablecoins, while separate platform arrangements require a fact-specific analysis. The opposite assumption is also unsafe: a platform cannot establish compliance simply by describing an issuer-funded benefit as an exchange reward.
A second risk is that providers may change product terms as implementation approaches. Reward rates, qualifying activities, customer eligibility, and service availability can change based on compliance assessments and commercial decisions. Users who depend on a particular yield should therefore review the product's current terms and understand whether rewards are discretionary, conditional, or subject to change.
A third risk concerns the broader regulatory transition. The OCC's final rule covers reserve assets, redemptions, risk management, reporting, custody, and supervision, while certain other implementation areas are being handled through separate rulemaking. Issuers and platforms may need to adapt to multiple requirements rather than treating the GENIUS Act as a single isolated rule.
Finally, rewards should not be confused with deposit interest or a guaranteed return. Stablecoins are digital assets, and the legal and financial protections available to holders differ from those associated with insured bank deposits. A reward-bearing product can introduce additional platform, counterparty, operational, and market risks. The absence of a blanket ban on a particular program does not establish that the product is safe or suitable for every user.
Join KuCoin's Futures Trading Competition
Looking to put your market analysis and trading skills to the test? Join the KuCoin Futures Trading Competition and explore an opportunity to compete with other traders.
Whether you are tracking AI-related stocks like Micron or following broader market trends, disciplined risk management remains essential when trading volatile assets. Before participating, review the competition rules, eligibility requirements, reward details, and trading conditions on the official event page. Futures trading involves substantial risk and may not be suitable for every trader.
Conclusion
The OCC's final GENIUS Act regulations clarify that covered payment stablecoin issuers cannot pay holders interest or yield solely for holding, using, or retaining their stablecoins. The rule, announced on October 21, 2026, takes effect on January 18, 2027, and also establishes requirements for reserves, redemptions, risk management, reporting, custody, and supervision.
The distinction between issuer payments and third-party rewards remains central. The final rule does not automatically prohibit every rewards program operated by a crypto platform, but neither does it grant blanket approval. Regulators can assess individual arrangements based on their substance, including whether a benefit effectively represents a prohibited issuer payment. As a result, platforms may review their reward structures and update product terms as the implementation date approaches.
For users, the practical priority is to understand who provides a reward, what activity qualifies for it, and what risks accompany the product. Stablecoins can remain useful for payments, transfers, and trading, but rewards should not be mistaken for guaranteed interest or insured deposits. Monitoring official OCC guidance and reading provider documentation will help users make better-informed decisions as the new framework takes effect.
FAQs
1. When does the OCC's final GENIUS Act rule take effect?
The final rule takes effect on January 18, 2027, according to the OCC's October 21, 2026 announcement. Affected organizations should review the rule and applicable transition requirements to determine what they must do before that date.
2. Does the GENIUS Act prohibit all stablecoin rewards?
No. The law prohibits covered issuers from paying interest or yield solely for holding, using, or retaining payment stablecoins. Separate rewards programs may be assessed individually, and their legality depends on the facts and structure of the arrangement.
3. Does the interest restriction apply to rewards paid in tokens?
Yes, the statutory language covers interest or yield paid in cash, tokens, or other consideration when it is solely connected to holding, using, or retaining the payment stablecoin. Paying a benefit in a token rather than cash does not automatically make it permissible.
4. Are stablecoins covered by the GENIUS Act the same as bank deposits?
No. Payment stablecoins are digital assets subject to a distinct legal framework. Holders should not assume that stablecoin balances or rewards have the same protections as insured bank deposits.
5. What should stablecoin users check before relying on a rewards program?
Users should review the provider's current terms, eligibility conditions, reward calculation, withdrawal restrictions, counterparty risks, and applicable legal disclosures. They should also check official regulatory guidance because product terms and regulatory interpretations can change.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or investment advice. Always conduct your own research before interacting with digital assets.