

Central Bank of Russia Rejects Dedicated Stablecoin Legislation: How CFA Rules Governing Digital Assets Impact Investors
Introduction
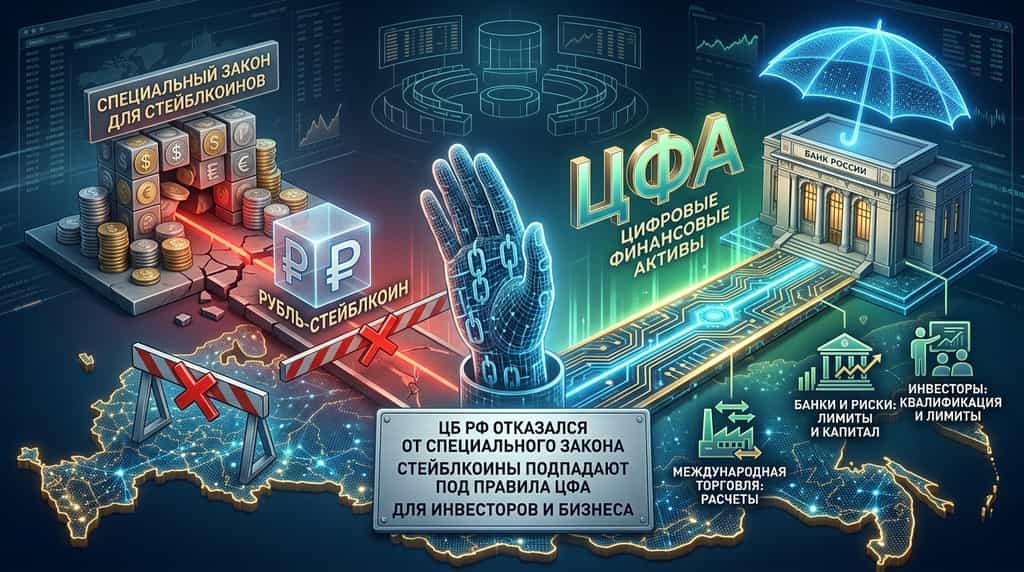
The Central Bank of Russia (CBR) announced on September 22, 2026, that it has abandoned plans to introduce a dedicated legal status and regulatory category for stablecoins. Rather than crafting bespoke rules for fiat-backed digital tokens, Russian regulators will maintain stablecoin oversight entirely within the existing legal framework for Digital Financial Assets (CFA). This strategic regulatory pivot reflects feedback from major domestic financial institutions, market participants, and corporate leaders who determined that specialized rules would impose unnecessary tax adjustments and operational hurdles.
Understanding the regulatory environment governing digital currencies in Russia is essential for institutional traders, cross-border businesses, and retail crypto investors navigating global digital asset markets. This comprehensive analysis evaluates the Central Bank of Russia's decision to maintain CFA governance, examines the operational mechanics of Russian digital financial asset laws, and explores the broader market implications for international cryptocurrency trading platforms like KuCoin.
Why Did the Central Bank of Russia Reject Dedicated Stablecoin Laws?
The Central Bank of Russia rejected standalone stablecoin legislation because domestic financial institutions and market participants expressed no demand for an isolated regulatory framework. Official statements confirmed on September 22, 2026, following the Moscow Financial Forum, revealed that commercial market participants confirmed existing legal structures under federal CFA laws already provide all necessary mechanisms to issue and settle asset-backed digital tokens.
Financial authorities initially floated a dedicated consultation paper exploring specialized rules for stablecoins—including fiat-pegged tokens issued by banks or specialized financial entities—to facilitate cross-border settlements. However, corporate feedback revealed that establishing a distinct legal entity for stablecoins would trigger a comprehensive tax regime revision, imposing unnecessary administrative burdens on domestic businesses. Sergey Shvetsov, Chairman of the Supervisory Board of the Moscow Exchange, noted that regulators will only revisit specialized stablecoin legislation if clear demand emerges from foreign trading partners seeking structured international trade mechanisms. Consequently, fiat-pegged tokens issued domestically will remain governed as monetary claims or securities under Russia's overarching Digital Financial Assets legal framework.
What Is the Role of CFA Rules in Governing Russian Digital Assets?
CFA rules serve as Russia's primary legal framework for managing tokenized real-world assets, debt instruments, equity tokens, and asset-backed digital currencies. Enacted under Federal Law No. 259-FZ and continuously refined by the Bank of Russia, the CFA regime allows authorized information system operators-such as commercial banks and licensed digital asset platforms—to issue digital rights pegged to currencies, precious metals, or commodities without creating new asset classes.
According to data published by the Bank of Russia in July 2026, the comprehensive crypto regulatory regime taking effect on September 1, 2026, integrates CFA platforms alongside broader digital asset operations. Under these active guidelines, Russian corporate entities can leverage ruble-pegged or commodity-backed digital rights for domestic treasury management and permit cross-border settlements. The key operational elements of the current CFA framework include:
-
Existing Tax Stability: Retaining stablecoin structures within the CFA perimeter prevents additional corporate tax reassessments and complex VAT restructurings for commercial issuers.
-
Issuer Accountability: Entities issuing digital financial assets must maintain 100% backing reserves, support 3-day redemption windows, and file regular disclosure reports directly to the central bank.
-
Infrastructure Integration: Established domestic exchanges and licensed repositories handle the issuance, custody, and settlement of digital financial assets directly.
How Does Russia's Decision Impact Foreign Stablecoins and Crypto Investors?
The CBR's decision preserves a clear distinction between domestic asset-backed digital rights and global, decentralized stablecoins like USDT or USDC. While domestic issuers utilize the CFA framework for structured corporate financing and trade settlement, global stablecoins operating on public blockchains fall under Russia's general cryptocurrency circulation laws enacted on September 1, 2026.
According to official regulatory releases from the Bank of Russia dated July 2026, non-qualified retail investors residing in Russia are subject to an annual purchase limit of ₽300,000 (approximately $3,300) for liquid digital currencies and foreign stablecoins across licensed domestic intermediaries, contingent on passing standard suitability testing. Qualified institutional investors face no annual investment caps but must fulfill rigorous investor verification requirements.
Crucially, while Russian law strictly prohibits the use of any digital currency—whether private stablecoins or public cryptocurrencies—as a medium of payment for domestic retail goods and services, international trade settlement guidelines permit Russian exporters and importers to utilize digital assets for cross-border transactions to mitigate international banking friction.
What Are the Key Differences Between Russian CFAs, Stablecoins, and the Digital Ruble?
Understanding the architectural and legal distinctions between Digital Financial Assets, private stablecoins, and the Central Bank Digital Currency (CBDC) is essential for evaluating Russia's broader monetary strategy. The Bank of Russia actively maintains three distinct categories of digital instruments, each serving specific operational roles within the domestic economy.
According to technical documentation published by the Bank of Russia in September 2026, the primary differences across these three digital asset categories are structured as follows:
| Feature / Dimension | Digital Financial Assets (CFA) | Private / Foreign Stablecoins | Digital Ruble (CBDC) |
| Issuing Authority | Licensed Commercial Banks & System Operators | Private Entities (e.g., Tether, Circle) | Central Bank of Russia (CBR) |
| Underlying Backing | Fiat Currency, Precious Metals, or Debt Claims | Fiat Reserves, Commercial Paper, Securities | Direct Sovereign Liability of Russia |
| Legal Classification | Digital Rights / Monetary Claims | Foreign Digital Currency / Crypto Asset | Official National Currency Form |
| Domestic Retail Payment Use | Strictly Prohibited | Strictly Prohibited | Fully Authorized Legal Tender |
| Cross-Border Trade Use | Permitted via Regulated Platforms | Permitted for Licensed Exporters/Importers | Subject to Bilateral Central Bank Agreements |
How Will Commercial Banks Handle Digital Asset Exposure Under Draft CBR Limits?
Russian commercial banks will face strict capital requirements when interacting with digital assets under new prudential rules proposed by the central bank. Based on draft supervisory regulations published by the Bank of Russia on September 22, 2026, the regulator intends to cap a bank's total risk exposure from cryptocurrencies and foreign digital instruments at 1% of its total capital.
The central bank's proposed framework introduces two maximum risk ratios—the N31 ratio for individual credit institutions and the N32 ratio for consolidated banking groups, to prevent systemic contagion from volatile digital assets into the traditional banking system. Key risk management criteria outlined in the draft rules include:
-
Extreme Risk Weighting: Direct cryptocurrency exposures, proprietary trading holdings, and derivative contracts will carry a heavy 1,250% risk weight for capital adequacy calculations.
-
Custodian Loss Exclusions: Client assets held in custody where the bank bears direct financial liability carry the 1,250% weight, whereas client positions where the bank bears no loss liability are excluded from the 1% cap and assigned a 50% risk weight.
-
Strict Compliance Enforcement: Banks must calculate exposure daily. Breaching the 1% ceiling on six or more operating days within a 30-day window empowers the central bank to impose severe corrective enforcement actions.
-
Reporting Timeline: Commercial banks will begin formal reporting under the N31 and N32 risk metrics starting January 2027, following a mandatory transition phase ending July 1, 2027.
What Does Russia's Stablecoin Strategy Mean for Global Crypto Markets?
Russia's choice to forego dedicated stablecoin legislation in favor of utilizing existing CFA channels highlights a broader trend among emerging markets toward utilizing tailored digital rights rather than replicating Western stablecoin frameworks. By streamlining legal processes around Digital Financial Assets, Russian regulators provide corporate entities with predictable settlement mechanisms without creating regulatory loopholes in foreign exchange management.
For international crypto markets, this regulatory policy maintains a high demand for liquid, globally traded stablecoins across decentralized and centralized platforms. As cross-border trade entities explore compliant channels for international commerce, liquidity remains heavily concentrated in global digital asset markets. Global crypto traders continue to leverage established exchange infrastructure to execute multi-currency transactions, manage portfolio risk, and maintain seamless liquidity access.
Beyond the Headlines: What KuCoin 5.0 Means for You
Market news moves fast — but where you act on it matters just as much. This October, KuCoin launches KuCoin 5.0, transforming KuCoin into a rebuilt platform. Here's what actually changes for you:
-
One account for everything. Older platforms split your money across separate "spot," "margin," and "futures" accounts and expected you to understand why. KuCoin 5.0's unified account removes that entirely — deposit once, and everything is simply there (only available to VIPs for now).
-
Stocks, indices, and commodities. KuCoin 5.0 expands beyond crypto into global markets. When crypto chops sideways and equities rally (or the reverse), you rotate in minutes instead of opening a brokerage account and waiting days for fiat rails.
-
Real-world assets (RWA). Tokenized exposure to traditional assets like commodities, right inside your crypto account. One of the fastest-growing segments in global finance is no longer reserved for institutions — you access it from the same balance you trade with.
-
Earn while you learn. Not ready to trade? KCUSD lets your stablecoins earn daily, auto-compounding interest. The lowest-stress way to put your idle deposit to work for 4% yield.
-
An AI assistant in plain language. Ask questions, get market context, understand what you're looking at — built into the platform, no jargon required.
-
An app that doesn't overwhelm. Faster, cleaner, and consistent — intuitive from the first tap, not after a tutorial.
-
Safety you can check, not just trust. A MiCAR-licensed EU entity, Proof of Reserves you can verify yourself, and internationally certified security (SOC 2 Type II, ISO 27001:2022).
Create your account in minutes — and start on the platform built for where crypto is going, not where it's been.
Conclusion
The Central Bank of Russia's decision to reject dedicated stablecoin legislation marks a decisive choice for regulatory efficiency over structural fragmentation. By maintaining all domestic asset-backed digital tokens under the established Digital Financial Assets (CFA) framework, Russian authorities have honored corporate feedback, avoided complex tax restructurings, and preserved predictable operational rules for institutional issuers. At the same time, recent prudential proposals—such as capping commercial bank crypto risk exposures at 1% of total capital—demonstrate the regulator's commitment to containing broader systemic risks while allowing controlled cross-border digital trade settlements.
As global crypto regulatory frameworks mature into distinct regional models, access to secure, liquid, and versatile trading platforms remains essential for international market participants. Understanding the legal distinctions between sovereign CBDCs, domestic asset-backed digital rights, and global stablecoins empowers traders to navigate shifting financial landscapes effectively. KuCoin continues to support global investors by delivering a transparent, highly secure ecosystem for seamless digital asset trading.
Frequently Asked Questions (FAQs)
What is a Digital Financial Asset (CFA) under Russian law?
A Digital Financial Asset (CFA) is a legally recognized digital right issued on a licensed blockchain or distributed information system in Russia. CFAs represent monetary claims, rights to exercise corporate equity, or claims on physical commodities and precious metals under Federal Law No. 259-FZ.
Can Russian citizens legally purchase foreign stablecoins like USDT?
Yes, Russian citizens can legally purchase foreign stablecoins through licensed intermediaries, subject to regulatory limits. Non-qualified investors are capped at purchasing up to ₽300,000 worth of liquid cryptocurrencies and stablecoins per year per intermediary after passing mandatory suitability testing, while qualified investors face no purchasing limit.
Are stablecoins allowed as a direct payment method inside Russia?
No, stablecoins and public cryptocurrencies cannot be used as a direct payment method for goods, services, or internal commercial contracts within the Russian Federation. Russian law mandates that the Russian Ruble remains the sole legal tender for internal domestic transactions, though digital assets are permitted for authorized cross-border foreign trade payments.
How does Russia's Digital Ruble differ from an asset-backed CFA?
The Digital Ruble is Russia's official Central Bank Digital Currency (CBDC), issued directly by the Central Bank of Russia as sovereign legal tender. In contrast, a CFA is a private or commercial digital financial instrument issued by licensed financial institutions or corporate entities, backed by collateral assets or monetary claims rather than sovereign liability.
Why did Russian businesses prefer CFA rules over new stablecoin laws?
Russian businesses preferred CFA rules because existing digital financial asset laws already provide adequate legal mechanisms for issuing asset-backed digital tokens. Creating a new, dedicated legal category for stablecoins would have required extensive revisions to corporate tax laws, imposing additional regulatory and compliance costs on market participants.
Disclaimer:The information provided on this page may originate from third-party sources and does not necessarily represent the views or opinions of KuCoin. This content is intended solely for general informational purposes and should not be considered financial, investment, or professional advice. KuCoin does not guarantee the accuracy, completeness, or reliability of the information, and is not responsible for any errors, omissions, or outcomes resulting from its use. Investing in digital assets carries inherent risks. Please carefully evaluate your risk tolerance and financial situation before making any investment decisions. For further details, please consult KuCoin’s Terms of Use and Risk Disclosure.