

Bank of Russia Raises Banks’ Liquidity Deficit Forecast to RUB 5.2 Trillion: What It Means for Deposits and Loans
Introduction
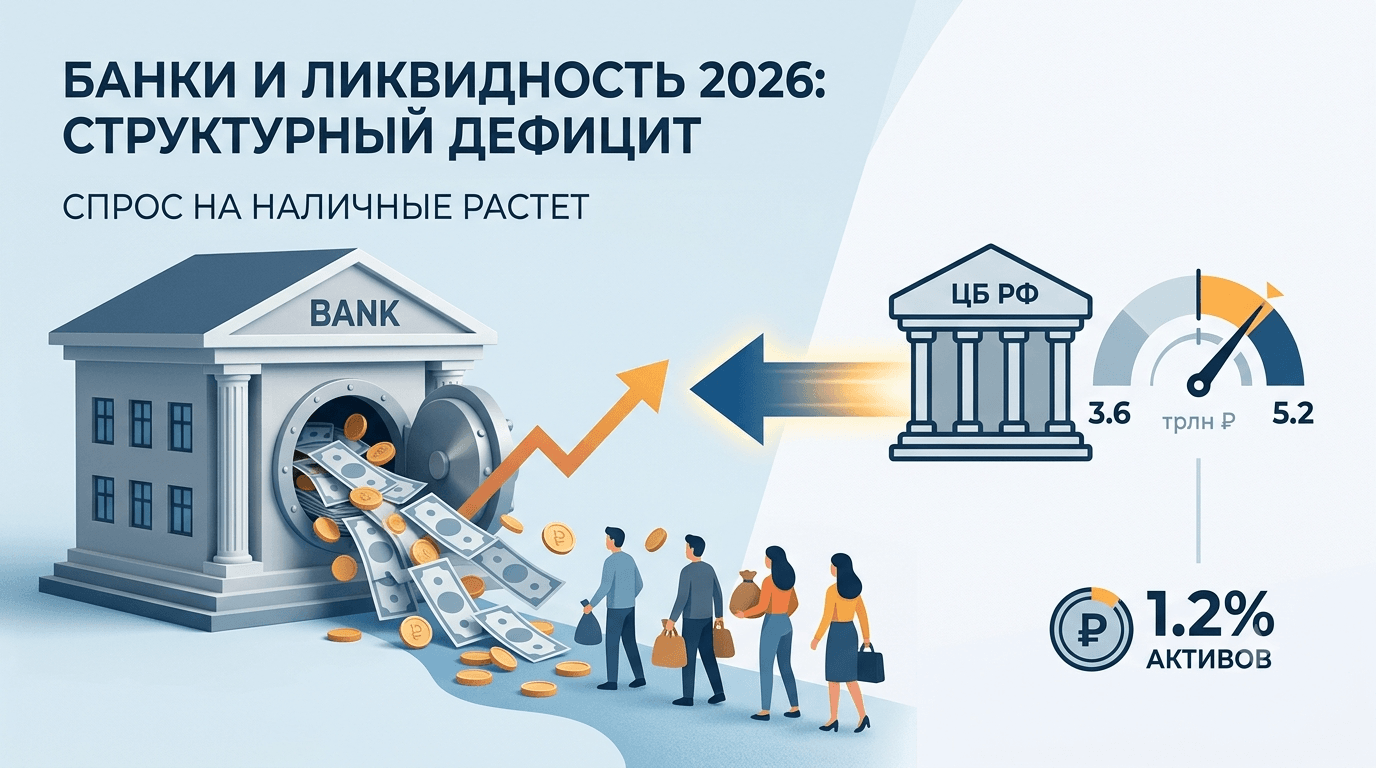
The Bank of Russia has raised the upper end of its 2026 forecast for the banking sector’s structural liquidity deficit from RUB 3.6 trillion to RUB 5.2 trillion. This is a significant adjustment, but it does not mean that Russian banks lack the funds needed to operate or that depositors face a threat of losing their money. According to the Bank of Russia, the deficit represents only 1.2% of banking-sector assets, and its impact is fully offset by the regulator’s operations. The main reason for the revision is that household demand for cash has grown faster than expected.
In other words, money has not disappeared from the economy: part of the deposits has been converted into banknotes and withdrawn from bank accounts. For customers, this means that attractive deposit rates may remain available, while borrowing costs are likely to decline slowly. This article explains what a structural liquidity deficit is, why the forecast was raised, and why the situation does not represent a banking crisis scenario.
What Does the Bank of Russia’s New Forecast Mean?
The new forecast means that, on average, banks may require RUB 4.0 trillion to RUB 5.2 trillion in structural liquidity during the December averaging period of 2026. Compared with the previous estimate of RUB 2.4 trillion to RUB 3.6 trillion, the range has been raised by RUB 1.6 trillion.
A structural liquidity deficit is not a bank loss or the amount of overdue loans. The indicator reflects the banking sector’s persistent need to borrow funds from the central bank when its own reserves and attracted resources are insufficient to support settlements, required reserves, and liquidity ratios.
The Bank of Russia calculates the current deficit as the difference between the regulator’s claims on credit institutions from liquidity-provision operations and its liabilities to banks through deposits and bonds. The calculation also includes the difference between balances in correspondent accounts and averaged required reserves.
This should be distinguished from an ordinary shortage of money at an individual bank. The structural indicator covers the entire sector and assumes that the regulator regularly provides financing through standard monetary-policy instruments. Therefore, a rise in the indicator alone does not indicate that banks are insolvent.
Why Was the Forecast Raised by RUB 1.6 Trillion?
The main factor is that actual demand for cash turned out to be higher than initially expected. The Bank of Russia revised its forecast after analyzing cash flows since the beginning of the year, not because of a sudden deterioration in the quality of bank assets [1].
The previous range was RUB 2.4 trillion to RUB 3.6 trillion. The new range of RUB 4.0 trillion to RUB 5.2 trillion shows that the regulator expects a larger withdrawal of funds from the banking system in the form of banknotes. At the same time, the required-reserve forecast assumes that reserves will grow in proportion to the expansion of the money supply.
Where Did the Money Leave the Banking System?
The money has mainly moved from deposits into cash rather than being destroyed or removed from the financial system. In August 2026, the amount of cash in circulation increased by RUB 0.4 trillion, exceeding the levels recorded in previous years.
The reasons are strongly seasonal. The holiday season continues in August, while households increase spending ahead of the new school year. Some people withdraw funds in advance to pay for travel, purchases, and everyday expenses in cash. When a bank gives a customer banknotes, its balance in a correspondent account at the Bank of Russia declines, causing the sector’s structural deficit to increase.
At the same time, cash’s share of the total money supply remains stable at 15.1%, according to materials published by the regulator in September 2026. This is an important detail: an increase in the absolute amount of cash does not mean that households are abandoning cashless payments on a mass scale or losing trust in banks.
Why Does the Seasonal Factor Matter?
Seasonal demand increases pressure on liquidity over a short period, but it does not necessarily create a long-term risk. After the holiday season ends, some cash returns to bank accounts, while part of the spending is offset by business receipts and wage payments.
Nevertheless, the regulator incorporates actual cash dynamics into its annual forecast. If elevated demand persists longer than expected, banks will need more refinancing operations. Therefore, the forecast revision reflects the Bank of Russia’s caution rather than a signal of uncontrolled panic.
Is There a Risk of a “Money Shortage” or Bank Failures?
There is no risk of a systemic “money shortage” or a wave of bank failures because of this indicator. The Bank of Russia has stated directly that growth in the structural deficit does not affect the stability of the banking sector because its impact is fully covered by liquidity-management operations.
The structural deficit equals 1.2% of banking-sector assets. According to the regulator, this is significantly below the levels observed from the second half of 2012 through early 2016. Consequently, the indicator should be assessed not only in ruble terms but also relative to the size of the entire banking system.
The Bank of Russia has several channels for supporting liquidity. They include auctions, standing facilities, repurchase operations, secured loans, and other instruments. Their purpose is to ensure that banks have access to ruble funds when temporary or structural factors reduce balances in correspondent accounts.
What Does the Current Liquidity Statistics Show?
As of September 16, 2026, the official banking-sector liquidity deficit stood at RUB 3,044.6 billion at the start of the day. This is a current estimate, not a new annual forecast. It shows how much liquidity the sector needs to borrow from the central bank after taking existing operations and required reserves into account.
The Bank of Russia separately explains that a positive value represents the amount of liquidity that credit institutions need to borrow from the regulator. A negative value would indicate a surplus, meaning excess funds in correspondent accounts in the absence of Bank of Russia operations.
In August, banks’ average market-based liquidity requirement reached RUB 5.2 trillion, compared with RUB 5.0 trillion in July. During the same period, the structural deficit increased by RUB 0.3 trillion. This trend requires monitoring, but it does not by itself indicate a solvency crisis.
How Will Banks’ Financing Needs Change?
Banks’ projected need to attract liquidity through Bank of Russia auctions during the December averaging period of 2026 has been raised by RUB 2 trillion, to RUB 8.0 trillion–RUB 9.2 trillion. This means that banks will probably turn to the regulator’s operations more frequently to manage their balance sheets.
The difference between the structural-deficit forecast and the need for auction liquidity is explained by the design of banking regulation. Banks need funds not only to cover a persistent liquidity outflow but also to meet required-reserve requirements, regulatory ratios, and short-term settlement needs.
According to the Bank of Russia, demand for loans through the main facility is also linked to the need to meet required-reserve requirements and comply with the national short-term liquidity ratio. In other words, auction operations serve a regular infrastructure function rather than an emergency one.
Why Can Banks Borrow from the Central Bank Even When the Sector Is Stable?
The central bank is the main counterparty in the money market and facilitates the redistribution of funds among banks. Even a stable bank may temporarily borrow from the regulator if its payments to customers exceed the inflow of funds from other operations on a given day.
Regular refinancing is not the same as rescuing a troubled institution. It allows the banking system to synchronize payments, reserves, and liabilities. Therefore, a larger volume of auctions indicates a greater financing requirement, but it does not prove that the quality of bank balance sheets is deteriorating.
What Does This Mean for the Key Rate and Market Rates?
In the short term, money-market rates are likely to move toward the upper part of the corridor around the key rate, while borrowing costs will decline slowly. A liquidity deficit raises banks’ cost of funding and increases their reliance on Bank of Russia operations.
Even if the key rate begins to decline, the transmission of that reduction to loans and mortgages may take time. Banks first need to stabilize the cost of their liabilities, attract sufficient deposits, and make sure that money-market conditions remain predictable.
This does not mean that the key rate will automatically rise because of a single forecast. The rate decision depends on inflation, inflation expectations, lending growth, demand, and other factors. The liquidity deficit is more likely to affect the speed at which the regulator’s decisions are transmitted to banking products.
What Will Change for Depositors?
For depositors, banks’ increased need for funding may support attractive deposit rates. Banks have an incentive to keep customer funds in accounts, especially when part of the money is being converted into cash and central-bank financing has a cost.
In practice, this may take the form of special short-term deposits, higher rates for new money, and stricter early-withdrawal terms. However, the highest rate does not always provide the best outcome: customers should compare the term, top-up options, interest capitalization, and deposit-insurance coverage.
Growth in the structural deficit is not a reason to withdraw a deposit immediately. On the contrary, the Bank of Russia’s official position indicates that the sector remains stable. Decisions about placing funds should take into account a person’s emergency reserve, financial goal and time horizon, and the terms of the specific product.
What Will Change for Borrowers and Mortgage Customers?
Borrowing conditions are likely to remain relatively tight, and a significant decline in loan and mortgage rates may be delayed. High bank funding costs are combined with restrictive monetary policy, so banks cannot reduce borrowing costs quickly merely because some cash returns seasonally to the banking system.
Consumer loans are particularly sensitive to funding costs and the assessment of customer risk. Mortgage rates depend not only on the key rate but also on down-payment requirements, collateral quality, government programs, and banks’ willingness to provide long-term financing.
Prospective borrowers should focus on the total cost of credit rather than the advertised rate alone. If repayments take up too large a share of income, even a small change in terms can materially affect a household budget. Waiting for lower rates should not replace an assessment of financial resilience.
Which Misconceptions Should Be Avoided?
The first misconception is that a structural deficit means that people are running out of money. In reality, the indicator describes the banking system’s liquidity balance and its need to borrow from the Bank of Russia.
The second misconception is that rising cash holdings indicate a mass bank run. The August increase of RUB 0.4 trillion was primarily connected with holidays and preparations for the new school year, while cash’s share of M2 remains at 15.1%.
The third misconception is that a deficit automatically leads to bank failures. The Bank of Russia states that the indicator equals 1.2% of assets and is fully covered by its operations. The risk at an individual bank should be assessed by looking at capital, asset quality, liquidity, and reporting rather than at one macroeconomic indicator.
The fourth misconception is that the RUB 4.0 trillion–RUB 5.2 trillion forecast means that banks will lose exactly that amount. It is an estimate of structural liquidity needs over a period, not a financial loss for the sector.
How Can You Monitor the Situation Without Panicking?
Several indicators should be monitored at the same time: the official liquidity balance, money-market rates, key-rate decisions, deposit dynamics, and reports on the quality of bank assets. A single indicator rarely provides a reliable forecast for a depositor or borrower.
It is also useful to check publication dates. The Bank of Russia’s current statistics are updated regularly, whereas the annual forecast changes when its assumptions are revised. These figures cannot be compared directly without considering their different time horizons.
Temporary cash outflows should also be distinguished from a sustained contraction in the deposit base. The former may be seasonal. The latter would require a separate analysis of household income, trust in banks, inflation expectations, and the attractiveness of alternative assets.
Beyond the Headlines: What KuCoin 5.0 Means for You
Market news moves fast — but where you act on it matters just as much. This October, KuCoin launches KuCoin 5.0, transforming KuCoin into a rebuilt platform. Here's what actually changes for you:
-
One account for everything. Older platforms split your money across separate "spot," "margin," and "futures" accounts and expected you to understand why. KuCoin 5.0's unified account removes that entirely — deposit once, and everything is simply there.
-
Stocks, indices, and commodities. KuCoin 5.0 expands beyond crypto into global markets. When crypto chops sideways and equities rally (or the reverse), you rotate in minutes instead of opening a brokerage account and waiting days for fiat rails.
-
Real-world assets (RWA). Tokenized exposure to traditional assets like commodities, right inside your crypto account. One of the fastest-growing segments in global finance is no longer reserved for institutions — you access it from the same balance you trade with.
-
Earn while you learn. Not ready to trade? KCUSD lets your stablecoins earn daily, auto-compounding interest. The lowest-stress way to put your idle deposit to work for 4% yield.
-
An AI assistant in plain language. Ask questions, get market context, understand what you're looking at — built into the platform, no jargon required.
-
An app that doesn't overwhelm. Faster, cleaner, and consistent — intuitive from the first tap, not after a tutorial.
-
Safety you can check, not just trust. A MiCAR-licensed EU entity, Proof of Reserves you can verify yourself, and internationally certified security (SOC 2 Type II, ISO 27001:2022).
Create your account in minutes — and start on the platform built for where crypto is going, not where it's been.
Conclusion
The Bank of Russia has raised its 2026 forecast for the banking sector’s structural liquidity deficit to RUB 4.0 trillion–RUB 5.2 trillion, an increase of RUB 1.6 trillion from the previous estimate. The main reason is stronger household demand for cash. In August, cash in circulation increased by RUB 0.4 trillion because of the holiday season and spending ahead of the new school year, while cash’s share of M2 remained at 15.1%.
The higher forecast does not mean that banks are becoming insolvent. The deficit equals 1.2% of sector assets, and the Bank of Russia offsets its effects through liquidity-management operations. The projected need to attract funds through auctions during the December period has been raised to RUB 8.0 trillion–RUB 9.2 trillion, reflecting the regular operation of the refinancing mechanism.
For depositors, this may mean that high deposit rates remain available. For borrowers, it may mean that loan and mortgage costs decline slowly. The main conclusion is straightforward: the situation requires monitoring, but the available data point to a controlled change in the structure of banking liquidity rather than a “money shortage” or a threat of mass bank failures.
Frequently Asked Questions
1. Could a liquidity deficit lead to restrictions on cash withdrawals?
A structural liquidity deficit by itself does not mean that withdrawal restrictions will be introduced. Banks obtain liquidity through Bank of Russia instruments, while ordinary customer transactions continue under the terms of the relevant account and applicable law.
2. Why Do Banks Need Required Reserves?
Required reserves help banks meet regulatory requirements and maintain the stability of settlements. Their size is considered when liquidity is assessed, so growth in the money supply may be accompanied by higher reserve requirements.
3. Will Cash Return to Bank Accounts After August?
Some cash may return after the holiday season and seasonal purchases end, but the exact amount depends on household behavior. The Bank of Russia takes actual trends into account and therefore does not assume that all banknotes will automatically return to the banking system.
4. Does a Liquidity Deficit Increase Bond Yields?
There is no direct or guaranteed relationship. Bond yields depend on the key rate, inflation expectations, maturity, credit risk, and investor demand. A liquidity deficit may affect the money market, but it does not determine the price of every bond.
5. Can Rising Liquidity Deficits Be Considered a Sign of Recession?
No. This indicator alone is insufficient to conclude that a recession is occurring. It reflects the banking system’s liquidity balance rather than output, employment, or household income. Assessing the business cycle requires a broader set of macroeconomic data.
Disclaimer : This material is provided for informational purposes only and does not constitute financial, investment, legal, or tax advice. Transactions involving cryptocurrencies and tokenized assets carry substantial risks — including price volatility, limited liquidity, counterparty exposure, and the potential for total loss of invested capital. Readers should conduct their own research and, where appropriate, consult a qualified professional before making any financial decisions.