

Russia's Venture-Capital Market in 2026: Why Investments Fell 48% and Where Capital Is Still Available
Introduction
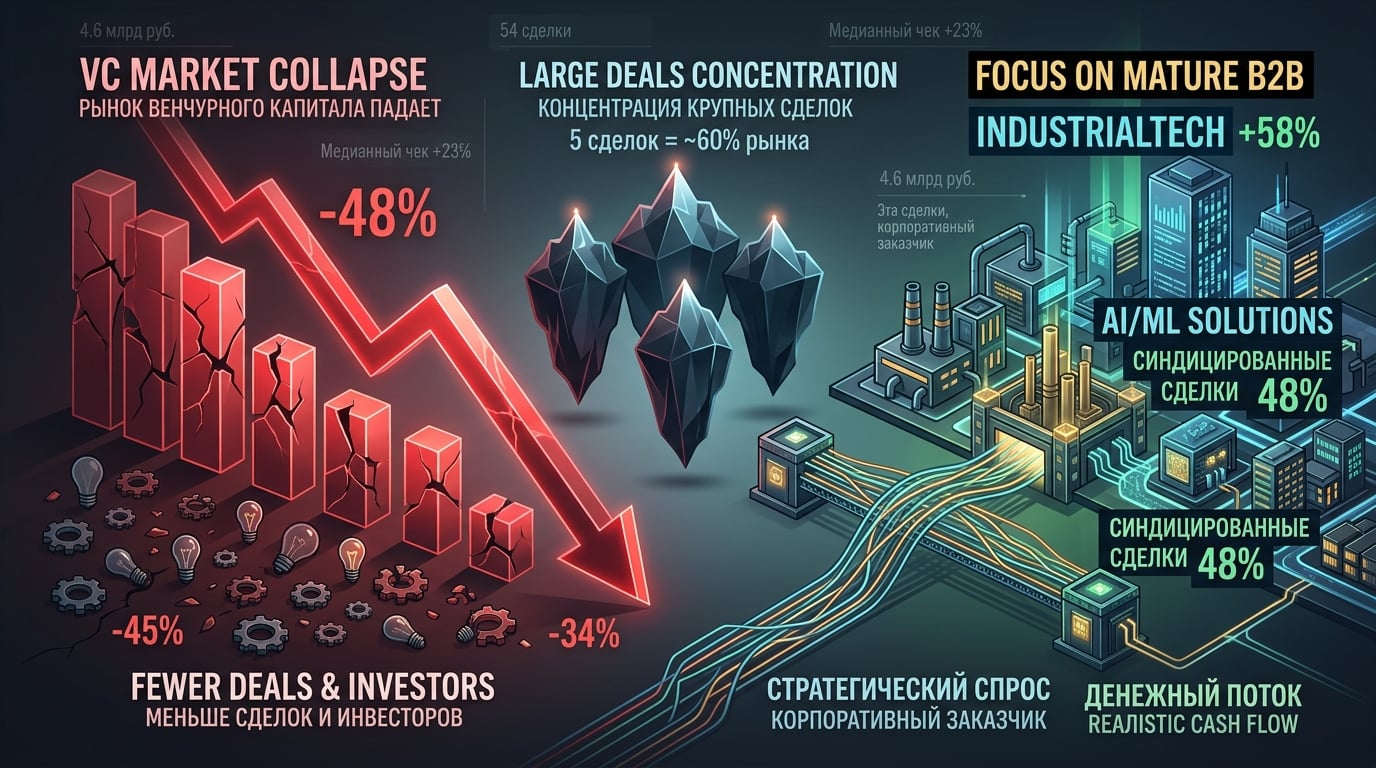
What happens to Russian startups when the market loses nearly half of its funding in six months? In the first half of 2026, venture investment in Russia fell 48% year over year to 4.6 billion rubles, while the number of deals declined 45% to 54 agreements. These figures from the Moscow Venture Fund show not the complete disappearance of venture capital, but a shift toward a more cautious model: investors are choosing mature companies, proven business models, and projects linked to industrial digitalization and import substitution. Large deals remain active because they account for most of the market volume. Venture investments are now more often directed toward B2B companies and technologies with clear revenue streams. Startup investments are returning only to areas where there is strategic demand, a corporate customer, and a realistic path to positive cash flow.
How Sharply Has Russia's Venture-Capital Market Contracted?
Russia's venture-capital market was 48% smaller in the first half of 2026 than a year earlier, but the decline in total volume was not accompanied by a comparable reduction in the average deal size. According to a study by the Moscow Venture Fund, investment volume amounted to 4.6 billion rubles, while the number of deals fell to 54, the lowest level since the beginning of 2023. This means that investors did not simply stop funding startups: they began completing fewer deals, preserving significant sums for a limited number of companies.
|
Metric
|
H1 2025
|
H1 2026
|
Change
|
|
Venture investment volume
|
Approximately RUB 8.8 billion
|
RUB 4.6 billion
|
-48%
|
|
Number of deals
|
Approximately 98
|
54
|
-45%
|
|
Average deal size for disclosed deals
|
RUB 95.2 million
|
RUB 94.4 million
|
Almost unchanged
|
|
Median deal size
|
Below the 2026 level
|
RUB 24.6 million
|
+23%
|
|
Active investors
|
50
|
33
|
-34%
|
The average deal size across 49 deals with disclosed values was RUB 94.4 million, compared with RUB 95.2 million a year earlier, meaning that it barely changed. At the same time, the median deal size increased 23% to RUB 24.6 million. The difference between the average and median figures is important: several large rounds materially increase the average, while the median better reflects the typical deal size.
The long-term trend looks even harsher. After reaching RUB 92 billion in 2022, the market declined to RUB 11 billion in 2023, then rose to RUB 17.1 billion in 2024 and fell to RUB 15 billion in 2025. At the same time, the number of annual deals decreased only slightly, from 167 agreements in 2022 to 182 in 2025. Therefore, the current crisis is expressed primarily through the compression of round sizes and the concentration of capital, rather than through the disappearance of entrepreneurial activity.
Why Do Five Deals Account for Nearly 60% of the Market?
The main feature of Russia's venture-capital market in 2026 is the extreme concentration of capital. The five largest deals accounted for approximately 60% of total investment volume, while the round for the company "Arkhitech AI" was estimated at around RUB 1.1 billion, or approximately 24% of the entire market over six months. One large round can therefore influence industry statistics more strongly than dozens of small seed investments.
This concentration has a dual meaning. On the one hand, it shows that major investors are still willing to finance technology companies when they see a scalable product, business demand, and validated economics. On the other hand, mid-sized and early-stage projects have fewer opportunities to obtain financing because funds prefer to allocate capital among a limited number of more easily understood investment cases.
High concentration does not mean that all five largest projects are equally attractive or that their results automatically reflect the condition of the entire industry. It means something else: any conclusion about market recovery must be assessed not only by total volume, but also by the number of deals, the median deal size, and the number of active investors. In the first half of 2026, all of these indicators point to caution.
How Has the High Cost of Capital Changed Investor Behavior?
The high cost of capital has become the main filter for venture deals. When low-risk instruments — bank deposits and government bonds — offer investors a clear return, a venture project must compensate not only for the possibility of loss but also for the long waiting period before exit. In the Moscow Venture Fund study, the high cost of capital and macroeconomic uncertainty are directly identified as factors limiting new investment.
For private capital, this creates a "venture-capital gravity" effect toward more predictable instruments. Investors compare not only a startup's potential return, but also the time required to recover their capital, the probability of another funding round, and currency and regulatory risks. As a result, a project with negative cash flow must demonstrate especially strong growth or strategic value to compete for capital with deposits and bonds.
The decline in active investors from 50 to 33 confirms that the market has become accessible to fewer participants. The remaining players have sufficient resources, industry expertise, and longer investment horizons. As a result, the selection process itself is changing: an attractive presentation is no longer enough, and the key arguments are revenue, repeatable sales, a corporate customer contract, and the ability of the business to operate without constant external financing.
Why Is the Exit Problem Deepening the Investment Decline?
Weak exit mechanisms turn venture capital into a long-term and illiquid asset. An investor may put money into a promising company but lack a clear scenario for selling the stake: the domestic IPO market remains limited, overseas listings are more difficult, and the number of large cross-border buyers is small. Therefore, project assessments increasingly include not only growth prospects, but also the question of who might acquire the stake in five or seven years.
The shortage of exits increases caution at the early stages. The longer capital remains tied up, the higher the requirements for corporate governance, legal structure, and reporting transparency. For a fund, this means a greater risk of holding an asset without an opportunity to lock in a profit. For a startup, it means the need to build a business that is attractive not only for the next funding round, but also for a strategic buyer from the outset.
This is why late-stage rounds accounted for RUB 2.9 billion across nine deals in the first half of 2026. In terms of deal count, early-stage rounds retained 83% of the market, but late-stage rounds accounted for 63% of the volume by value. Investors formally continue to support early-stage companies, but they direct the largest amounts toward projects with proven models and a shorter path to scaling or a potential exit.
Which Sectors Are Receiving Funding During the Downturn?
Capital is concentrating in IndustrialTech, enterprise software, and AI/ML-based solutions because these segments are linked to business productivity, import substitution, and concrete demand from organizations. According to ICT.Moscow, investment in IndustrialTech increased 58% to RUB 1.9 billion, while funding for Business Software rose 160% to RUB 1.3 billion. At the same time, one large deal accounted for 86% of enterprise-software volume, again highlighting the impact of concentration.
IndustrialTech attracts investors because it can be integrated into real production processes. Projects in industrial automation, robotics, engineering software, and digital control can generate revenue from a limited number of large customers. For a fund, this does not always imply rapid growth, but it improves the predictability of contracts and makes the technology part of critical infrastructure.
Business Software also fits the market's new logic. A B2B product is easier to assess through contract value, customer retention, recurring revenue, and cost savings for the client. Among the companies that raised funding, 83.7% of disclosed projects belong to the B2B segment. This indicates a shift away from mass-market consumer applications toward solutions that help companies reduce costs or maintain operational continuity.
Artificial intelligence and machine learning remain an important technological layer. Among companies that disclosed their technology, 58.1% are developing AI/ML-based solutions, while 61.2% of all funded companies belong to the IT sector. However, the AI label alone does not guarantee investment. Under current conditions, capital goes not to every model, but to a product embedded in a business workflow, supported by data and paying customers, and capable of delivering a measurable effect.
Why Have Syndicated Deals Become the Standard for Capital Protection?
Syndicated deals allow investors to distribute financial risk and expertise among multiple participants. Their share increased to 48% from 44% a year earlier, while the number of active investors fell to 33. This combination shows that the market has not merely become less active: it has begun using collective structures more often for large and complex investments.
Syndication gives a startup access to a larger amount of capital and several sources of expertise. One participant may help with industrial contacts, another with financial controls, and a third with hiring or access to corporate customers. For investors, this is a way to reduce individual risk without completely excluding promising deals.
However, the syndicated model does not eliminate the market's problems. It can slow decision-making, complicate the coordination of rights, and create several centers of influence on the board of directors. Therefore, the quality of legal documentation, the allocation of authority, and the rules for subsequent rounds become more important than in a bilateral deal.
What Must Change for Early-Stage Venture Capital to Recover?
The recovery of early-stage investment depends primarily on a sustained reduction in the cost of financing and the introduction of incentives that compensate for high risk. In the study, citing Vitaly Polekhin, president of Investoro, a predictable decline in the key interest rate and borrowing costs is identified as a key condition for a turning point. Such a decline could return some capital from deposits to riskier assets.
Lower rates alone will not be enough. The market needs tax incentives for investors working with seed-stage projects, as well as specialized early-stage financing instruments. These mechanisms could increase the number of first checks if they are tied to transparent selection criteria and do not replace private expertise with administrative allocation of funds.
A new exit framework is equally important. Russian startups need clear routes to acquisition by a strategic investor, the sale of a stake to a larger fund, or a public listing. As long as the exit remains uncertain, funds will demand a higher risk premium, while founders will face stricter financing terms.
How Should the Market Decline Be Interpreted Without Drawing the Wrong Conclusions?
A 48% decline does not prove that Russia's venture-capital market has ceased to exist. It shows that capital has become selective and has shifted from the logic of "burning money for growth" toward cash flow, industrial demand, and strategic necessity. This is indicated by the increase in the share of private funds to 67%, the growing role of late-stage rounds, and the concentration of capital in IndustrialTech, B2B, and AI/ML.
When assessing the next period, it is important to examine several indicators simultaneously. An increase in volume with no change in the number of deals may result from a single megadeal. An increase in the number of deals accompanied by a decline in the median deal size would indicate broader activity, but not necessarily better financing quality. A genuine recovery will be visible through simultaneous growth in the number of deals, active investors, early-stage checks, and exit opportunities.
Regional concentration also requires attention. Moscow accounted for 80% of market volume, or RUB 3.7 billion, compared with 62% in 2025. St. Petersburg and the Leningrad Region accounted for 5%, Sverdlovsk Region for 4%, and Tatarstan for 2%. The more strongly capital is concentrated in one center, the more dependent national statistics become on several deals in the capital, and the more difficult it becomes for regional projects to attract early-stage financing.
KuCoin Offers A More Stable Option in A Volatile Market
If you worry about the frequent ups and downs in the market, and pursue a more stable option to earn money passively, KuCoin is the right place to come:
Simple Earn: Deposit and withdraw tokens anytime, earning stable returns.
Kucoin Earn: Earn stable profits with professional asset management.
Hold to Earn: Earn rewards by holding assets in Funding, Trading, Margin, Futures, Mining, and Unified Accounts.
Staking: Unlock the earning potential of on-chain assets.
Advanced Investments: Advanced Investments offer a variety of structured products to help your money grow in any market.
Shark Fin: Principal Protection and Guaranteed Gains
Dual Investment: Buy low and sell high with transparent return calculations.
Snowball: High yields, with price protection.
Discount Buy: Buy crypto at discount prices.
KCS Loyalty: Level up to enjoy exclusive perks by staking ≥ 1 KCS.
KuCoin Wealth: Discover future value and begin your smart investing journey.
KCS Benefits: Hold and stake KCS to access benefits across the platform.
KCS Staking 2.0: Participate in KCS on-chain governance to earn yield.
Conclusion
Russia's venture-capital market contracted to RUB 4.6 billion in the first half of 2026, losing 48% of its year-over-year volume. The number of deals fell 45% to 54, while the number of active investors declined from 50 to 33. At the same time, the market did not disappear: approximately 60% of capital was concentrated in the five largest deals, the share of syndicated rounds rose to 48%, and private funds provided 67% of all investment.
The main structural shift is the move from broad growth financing to selective investment in mature and strategically important projects. IndustrialTech, Business Software, and AI/ML gained an advantage because of their links to import substitution, industrial demand, and B2B digitalization. At the same time, investors are avoiding companies without revenue, a clear business model, or a realistic exit scenario.
Recovery will depend on a predictable decline in the cost of capital, tax incentives for early-stage investment, the development of seed funds, and the emergence of new exit mechanisms. Therefore, the next indicator of market health will not be a single large deal, but sustained growth in the number of investors, early-stage rounds, and independent sources of financing.
Frequently Asked Questions
1. How Is the 48% Decline in Russia's Venture-Capital Market Calculated?
The figure compares investment volume in the first half of 2026 with the corresponding period of 2025. According to the Moscow Venture Fund, the current volume amounted to RUB 4.6 billion, which was 48% lower year over year.
2. Why Did the Average Deal Size Barely Change Despite the Market Decline?
The average deal size for disclosed transactions was RUB 94.4 million, compared with RUB 95.2 million a year earlier. Total volume declined mainly because there were fewer deals, rather than because each investment became proportionally smaller.
3. What Does a Syndicated Venture Deal Mean?
It is a deal in which several investors jointly finance one project. They combine capital and expertise to distribute risk and gain access to a round that might be too large for a single participant.
4. Which Russian Region Attracted the Most Venture Investment?
Moscow retained the lead, accounting for approximately 80% of market volume, or RUB 3.7 billion, and 63% of the number of deals in the first half of 2026.
5. Can AI/ML Be Considered the Main Winner of Russia's Venture-Capital Market?
AI/ML is one of the most prominent technology areas: 58.1% of companies that disclosed their technology are developing solutions in this field. However, the main concentration of capital is not limited to AI; it is also forming around IndustrialTech and enterprise software.
Disclaimer : This material is provided for informational purposes only and does not constitute financial, investment, legal, or tax advice. Transactions involving cryptocurrencies and tokenized assets carry substantial risks — including price volatility, limited liquidity, counterparty exposure, and the potential for total loss of invested capital. Readers should conduct their own research and, where appropriate, consult a qualified professional before making any financial decisions.